
What a Spending Audit Reveals That Your Budget Never Will
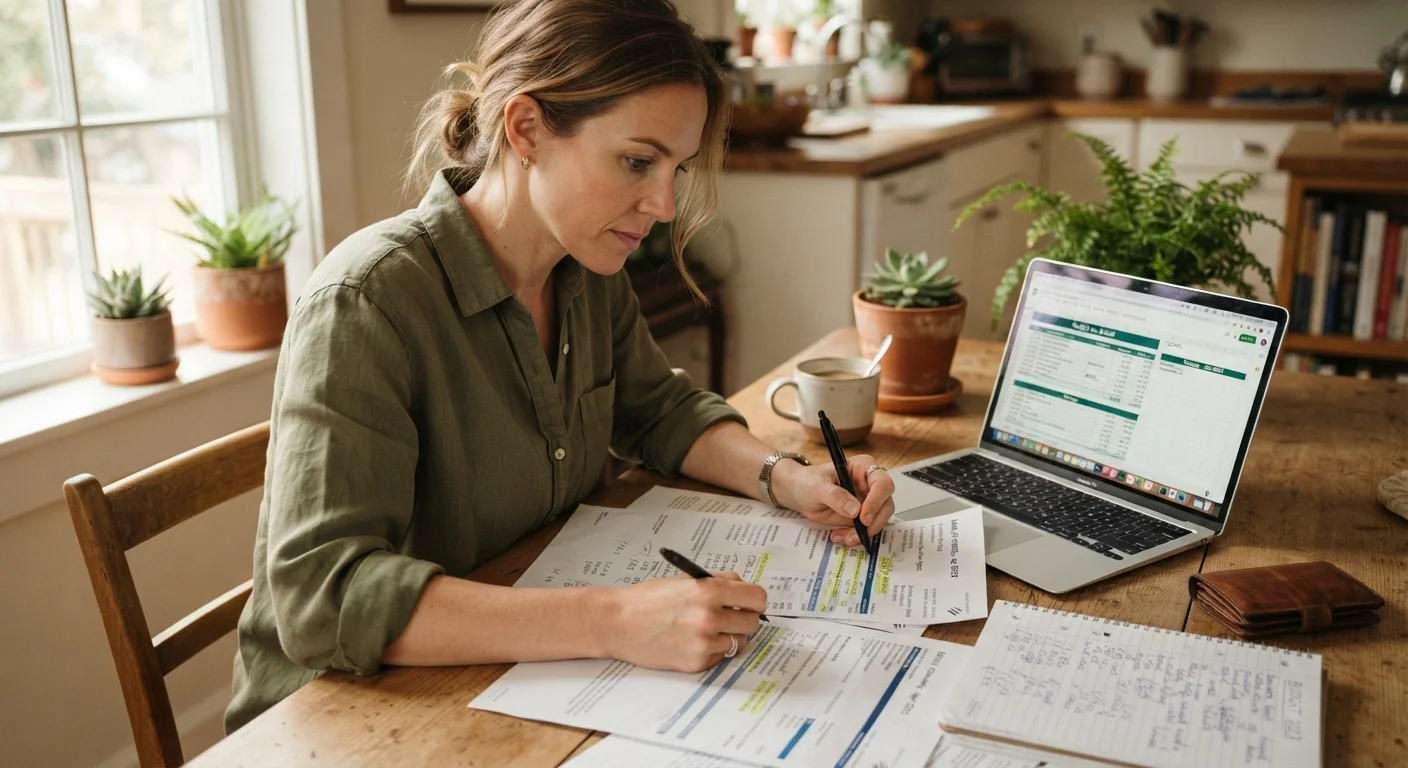
Photo credit: readerspanel.com
In this article
A spending audit compares what you planned to spend with what you actually spent. Here is how to run one and what patterns to look for.
Key Takeaways
- A spending audit compares actual transactions against your planned budget to find gaps.
- Most people consistently underestimate spending in two or three specific categories.
- Recurring charges are the most common source of overlooked spending.
- You only need one to three months of bank and credit card statements to start.
- The goal is pattern recognition, not perfection or guilt.
What a spending audit actually is
A budget tells you where you intend money to go. A spending audit tells you where it actually went. The two are almost never identical, and the distance between them is where most financial leakage lives.
Unlike a budget review, which typically compares category totals, a spending audit goes line by line through real transactions. It surfaces charges you forgot were on autopay, categories where you consistently overspend, and expenses that belong in no category at all because you never planned for them. For a broader look at how to build the tracking habit that makes audits easier, see spending tracker setups worth knowing.
A spending audit is general financial information, not personalized financial advice. For decisions specific to your situation, consult a licensed financial professional.
What you need before you start
Pull together one to three months of statements from every account where money moves: checking, savings, and all credit cards. Three months gives you enough data to see patterns rather than one-off anomalies. One month works if you just want a starting point.
You also need your written budget, or at minimum a list of what you expected to spend in each category. If you do not have one, write down your best guesses before you look at the statements. Guessing first and checking second is where the audit becomes informative.
What you will need
How to run the audit
List every account that sees regular transactions
Write down every checking account, savings account, and credit card you used during the period you are auditing. Include accounts you rarely use. A single overlooked card can hide significant spending.
Categorize every transaction
Go through each statement line by line and assign every transaction to a category. Use the same categories your budget uses. If a transaction does not fit anywhere, create an "unplanned" category rather than forcing it into a category where it does not belong.
Common categories: housing, groceries, dining out, transportation, subscriptions, healthcare, clothing, entertainment, personal care, and household supplies.
Total each category and compare to your budget
Add up what you actually spent in each category, then subtract your budgeted amount. Write the difference next to each line. Positive numbers mean you spent more than planned; negative numbers mean you spent less.
Audit your recurring charges specifically
Go back through the statements and highlight every charge that appeared in the same amount more than once. These are your subscriptions and automatic payments. List each one and ask whether you actively used the service in the period covered.
Recurring charges are the most common source of forgotten spending because they require no decision each month.
Identify your top three overspend categories
From your comparison, pick the three categories with the largest positive gaps between actual spending and budgeted amounts. These are your focus areas. Write one sentence describing what drove the overspend in each. Specific language matters here: "I ordered lunch at work four days a week instead of two" is more actionable than "I spent too much on food."
Adjust your budget to reflect reality, then decide what to change
Update your budget figures to reflect what you actually spent, unless you have a concrete, specific reason to believe the number will change. Then decide separately which categories you want to reduce and by how much. These are two different decisions. First, make the budget accurate. Second, make choices about what you want to adjust going forward.
For more structure on building a workable personal budget, the budgeting basics hub covers the full range of planning approaches.
What the patterns reveal
Most people who complete an audit find surprises in the same places: food (the split between groceries and dining out is almost always different from what people expect), subscriptions, and what can loosely be called "convenience spending" (delivery fees, last-minute purchases, parking).
The patterns your budget categories reveal matter more than any single transaction. A one-time splurge is not a problem. A pattern of consistent overspending in a category means the budget figure for that category was wrong, not that you failed.
Discretionary spending warrants particular attention because it is the category people most consistently underestimate. Discretionary spending often contains more flexibility than people realize, but only once you can see it clearly. If your audit covers household expenses broadly, the annual home expense checklist can help you catch predictable costs you may have left out of next year's plan entirely.
Vehicle costs are another area worth isolating. Fuel, insurance, parking, tolls, and maintenance often land in different categories or get absorbed into a vague "miscellaneous" bucket. Pulling those together gives you a real picture of what car ownership actually costs month to month. The real costs of owning a car hub has more detail on what to include.
Author
Smart Shopping Editorial Team
Smart Shopping Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →