
Budgeting as a Couple: A Practical Framework for Shared Financial Goals
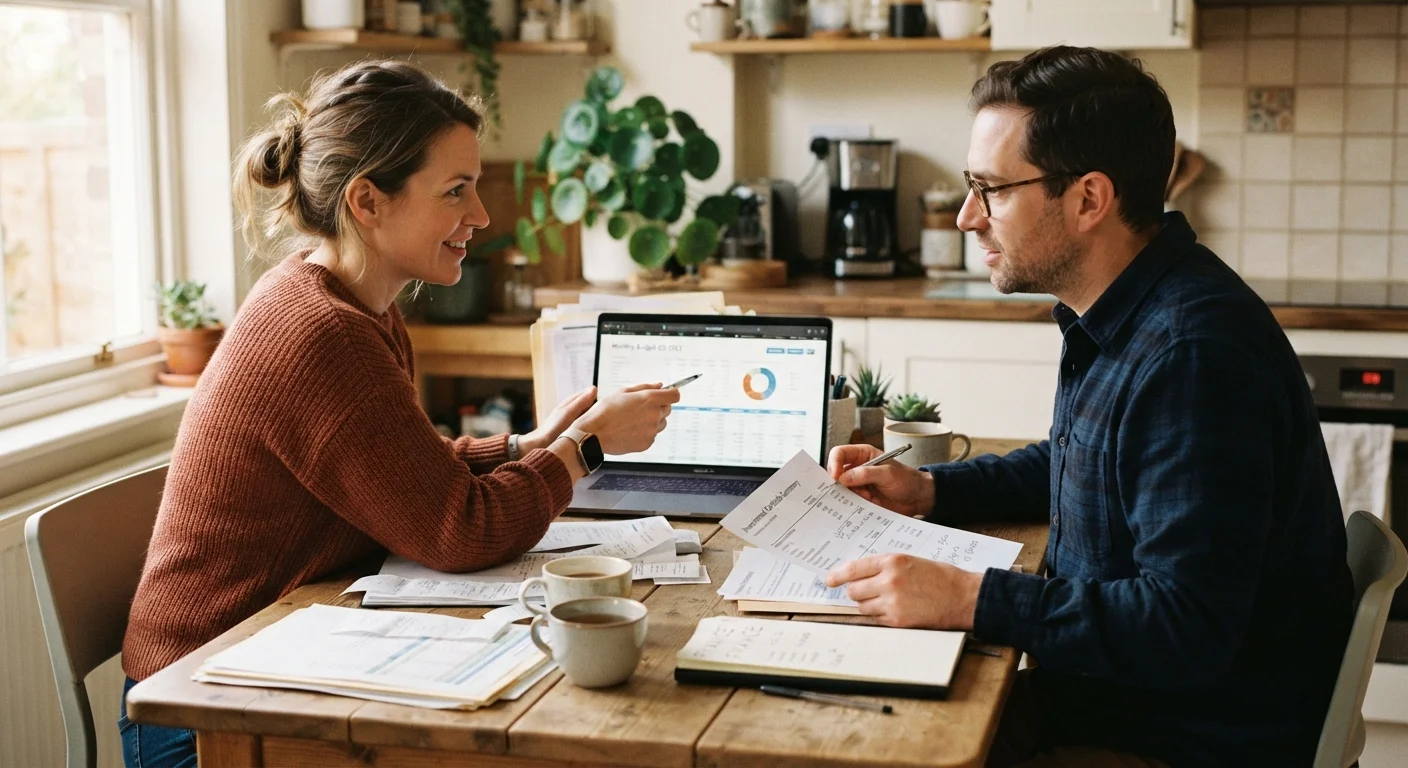
Photo credit: readerspanel.com
In this article
Combining finances with a partner involves more than merging bank accounts. A step-by-step approach to building a shared budget both people can commit to.
Key Takeaways
- A shared budget only works if both partners disclose all income, debts, and recurring expenses upfront.
- Agreeing on financial goals before setting spending limits reduces conflict later.
- Most couples benefit from a combination of joint and individual accounts rather than full merging.
- Regular budget check-ins, not just an annual review, keep spending aligned with agreed priorities.
- This article is general financial information, not personalized financial advice.
Why joint budgeting is harder than it looks
Two people rarely arrive at a shared household with identical spending habits, debt loads, or financial expectations. One partner may have grown up in a household where money was rarely discussed; the other may have detailed records going back years. Those differences do not disappear when you start sharing expenses. They show up as friction over what counts as a necessary purchase or how much of a raise should go toward savings versus quality of life.
A shared budget does not eliminate those differences. It gives both partners a visible, agreed-upon structure so that spending decisions have a reference point instead of triggering a judgment call every time. The framework below works whether you are merging finances for the first time or overhauling a system that has been running on informal agreements for years.
This article provides general financial information for educational purposes only. It is not personalized financial advice. For guidance specific to your situation, consult a licensed financial professional.
What you will need
How to build your shared budget
Put every number on the table
Both partners should list all sources of income (gross and net), every debt with its current balance and interest rate, and every recurring monthly obligation. This includes student loans, car payments, credit card minimums, subscriptions, and any informal financial commitments such as money sent to family members regularly.
Withholding any figure, even an uncomfortable one, will produce a budget that does not reflect reality and will require a harder conversation later.
Agree on shared financial goals before writing a single number
Before allocating dollars, both partners should state their individual financial priorities and then identify which ones overlap. Common areas include an emergency fund target, a timeline for paying off a specific debt, a savings goal for a home down payment, or a retirement contribution rate.
Where priorities differ, note the gap without resolving it yet. The budget structure in later steps will give you a mechanism for handling competing goals. For a broader framework on matching goals to timelines, see how to align your money with your timeline.
Map fixed and variable expenses to combined income
Add both partners' net monthly income, then list all fixed expenses (amounts that do not change month to month) first: housing, loan minimums, insurance premiums, and any fixed subscriptions. Subtract that total from combined income to find the amount available for variable spending and savings.
Variable expenses (groceries, gas, dining, clothing) should be estimated from the three months of statements gathered in the prerequisites. Average the actuals rather than guessing. The complete guide to household budgeting has a full category checklist that can help you avoid overlooking irregular expenses such as vehicle registration or annual insurance premiums.
Choose an account structure that matches how you both operate
There is no single correct account setup for couples. Three common arrangements are: fully joint (all income and spending flows through shared accounts), fully separate (each partner manages their own money and splits bills by formula), and a hybrid approach (each partner keeps a personal account and contributes a set amount to one joint account for shared expenses).
The hybrid model tends to reduce friction because each partner retains some financial autonomy while covering shared obligations from a transparent, agreed-upon pool. See how couples can budget together without arguments for a detailed look at how each structure plays out in practice.
Allocate money to goals and set spending limits
With fixed expenses covered and an account structure chosen, assign specific dollar amounts to each shared goal identified in step 2. Treat goal contributions as fixed line items in the budget, not as leftovers after spending. What remains after fixed expenses and goal contributions is the available spending budget for variable categories.
If contributions to every goal leave too little for variable spending, return to step 2 and rank goals by priority. One of the goals will need a longer timeline or a lower monthly contribution for now. For a structured way to think about which budgeting method fits your situation, the comparison of the 50/30/20 rule versus the envelope method can help you choose a framework for categorizing the variable portion.
Set a recurring check-in schedule
Schedule a monthly budget review of 20 to 30 minutes where both partners look at actual spending against the plan. The purpose is not to critique individual purchases but to see whether the category totals held and whether any adjustments are needed for the coming month.
A quarterly review should address bigger questions: Are shared goals on track? Has either partner's income or expenses changed significantly? Does the account structure still work? Automating transfers to savings and goal accounts, as described in this setup walkthrough for automating finances, can reduce the manual effort between check-ins.
Personal spending money reduces conflict
Many couples find it helpful to give each partner a set amount of personal spending money each month with no reporting required. Even a modest amount per person removes the feeling that every small purchase is subject to review. This does not need to be equal in dollar terms, but both partners should agree the amounts are reasonable.
Adjusting when circumstances change
A budget written once and never revised is a plan for one version of your life. Income changes, debts get paid off, and new expenses appear. The check-in schedule in step 6 catches small drift, but larger life changes (a job change, a move, a child) require a full rebuild starting from step 1.
If one partner's income drops significantly, the framework in single-income household budgeting covers principles that apply to households temporarily or permanently running on reduced income. For households where money is genuinely tight rather than just newly reorganized, budgeting on a tight income addresses the specific pressures that standard budgeting advice tends to skip.
The annual home expense checklist is worth running through once a year to catch predictable costs that get overlooked in month-to-month tracking.
Author
Smart Shopping Editorial Team
Smart Shopping Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →