
The Real Meaning of a "Needs vs. Wants" Budget
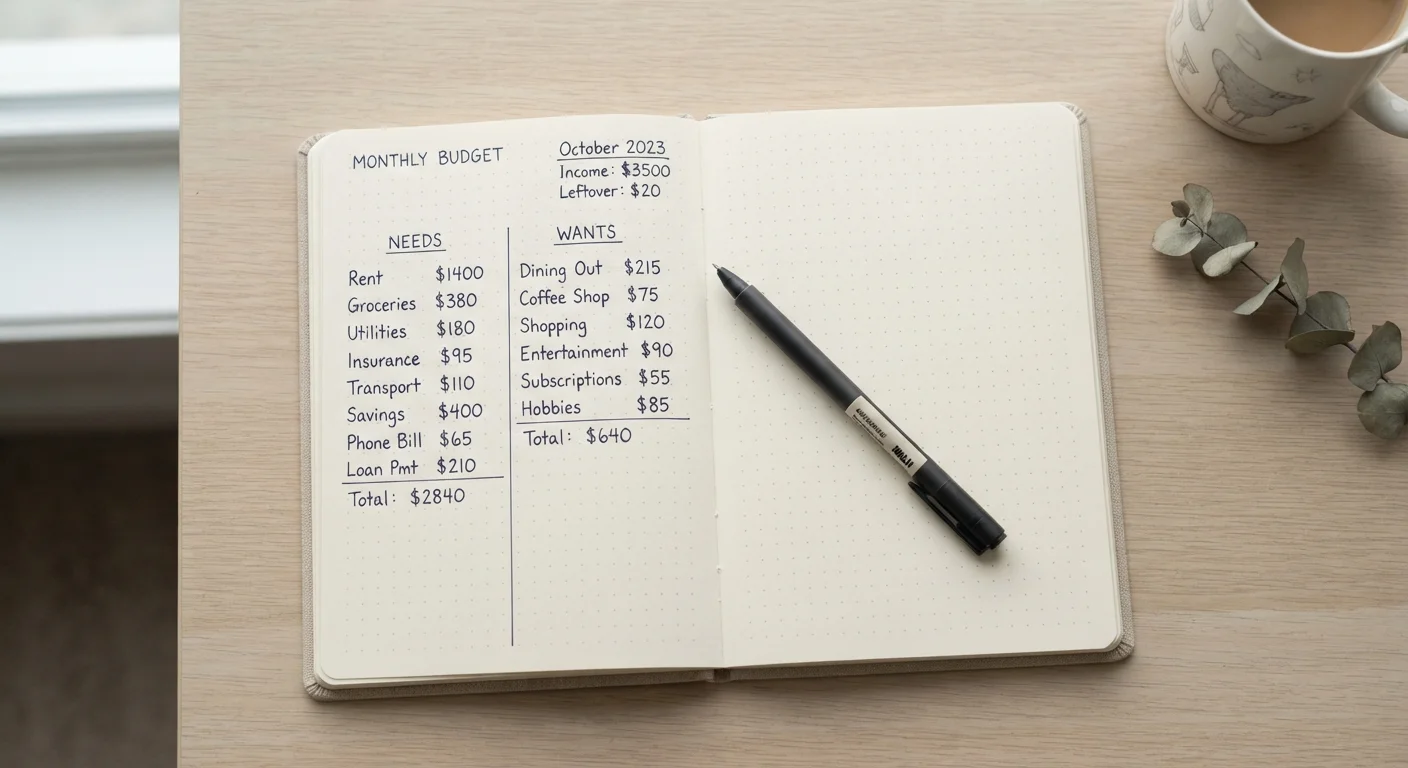
Photo credit: readerspanel.com
In this article
"Needs vs. wants" sounds simple, but the line blurs quickly. This explainer clarifies the distinction and shows how to apply it honestly in your own budget.
Key Takeaways
- Needs are expenses required for basic stability; wants improve comfort or enjoyment but are optional.
- The line between needs and wants is not fixed and depends on your income, location, and life situation.
- Misclassifying wants as needs is one of the most common reasons budgets fail to free up savings.
- Honest categorization matters more than perfect categorization when building a workable budget.
- Some expenses have a need component and a want component, and splitting them is often the most accurate approach.
Why the distinction matters more than it seems
Most people learn the needs vs. wants concept early and assume they already apply it. In practice, spending habits accumulate over time without much review, and expenses that started as wants often get reclassified as needs simply because they have been around long enough to feel essential.
This reclassification is rarely deliberate. A streaming subscription added during a slow month becomes a household fixture. A premium phone plan chosen for convenience stops feeling optional. Over time, the "needs" column expands without a corresponding increase in income, and the budget tightens without any clear explanation.
The distinction matters because it is the first honest accounting of where your money is going. Without it, you cannot accurately identify where flexibility exists. What your budget categories reveal about your habits is often more useful than the categories themselves, and the needs vs. wants split is where that analysis starts.
What actually counts as a need
A need, for budgeting purposes, is an expense you cannot reasonably eliminate without losing basic stability: housing, utilities required to live safely, groceries, health coverage, and transportation necessary for work. These are not lifestyle preferences. They are the baseline costs of staying housed, fed, healthy, and employed.
The difficulty is that needs are defined by your specific circumstances, not by a universal list. Someone who lives in a rural area with no public transit has a genuine transportation need that someone in a walkable city with subway access may not. A parent with young children has food and childcare costs that a single adult does not. Needs are context-dependent, which is why comparing your budget to a generic template rarely works.
When location changes what counts as a need
The same expense can be a need in one city and a want in another. A car payment is often unavoidable in areas with limited public transit, while in a dense urban area it may be entirely optional. When evaluating your own categories, your local infrastructure and cost of living matter as much as any general budgeting framework. Smart budgeting strategies account for this variation rather than applying a single national standard.
Where needs do tend to have clear limits is in the quality or tier of spending. The need is for shelter: the want is for a larger apartment than you require. The need is for food: the want is for a premium grocery budget when a more modest one would cover nutrition adequately. Separating the baseline from the upgrade is where much of the useful budget work happens.
Where the line blurs in everyday spending
Several common expense categories sit in ambiguous territory, and being honest about them is the core skill the needs vs. wants framework builds.
Internet access is close to a need for most working adults, especially those who work remotely or manage finances, healthcare, or job searching online. A basic plan is a need; the highest-speed tier available is usually a want.
Clothing is a need in its basic form. A functional wardrobe appropriate for work and weather is necessary. Buying beyond that, whether for variety, fashion, or preference, is a want.
Dining out is almost always a want, even when it feels like a time-saving necessity. Prepared food at a restaurant or delivery service costs more than home cooking for the same calories. Convenience has a price, and that price is a want-category expense.
Insurance is generally a need, but coverage levels involve want decisions. Health insurance is a need; supplemental coverage with every optional rider is partly a want. The same logic applies to auto and renters insurance: basic adequate coverage is a need, excessive add-ons are not.
Fixed and variable expense categories add another layer of complexity, because many want-category expenses are fixed in structure even though they are optional by nature.
How to apply this honestly in your own budget
The most productive way to use the needs vs. wants framework is to go through your last two or three months of actual spending, not a list you write from memory. Memory systematically underestimates wants and overestimates needs because people tend to remember spending in the most favorable light.
For each expense, ask whether eliminating it would create genuine instability: lost housing, lost income, a health consequence, or inability to meet a legal obligation. If the answer is no, it belongs in wants, regardless of how much you value it or how long you have been paying it.
If a budget built on honest categorization still feels unworkable, the problem is usually not the framework. It is either that income is insufficient relative to true needs, or that the want spending is larger than it appeared. A budget that feels too tight often reflects one of those two issues rather than a flaw in the budgeting method itself.
Tracking how your needs and wants breakdown shifts month to month can also show patterns that a single snapshot misses. Net worth over time reflects the cumulative result of those monthly decisions, which is why getting the categories right compounds in value.
This article is for general informational and educational purposes only and does not constitute personalized financial advice. Consult a qualified financial professional for guidance specific to your situation.
Frequently Asked Questions

Author
Personal Finance Editorial Team
Personal Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →