
When Fixed and Variable Expenses Blur: Rethinking How You Categorize Your Budget
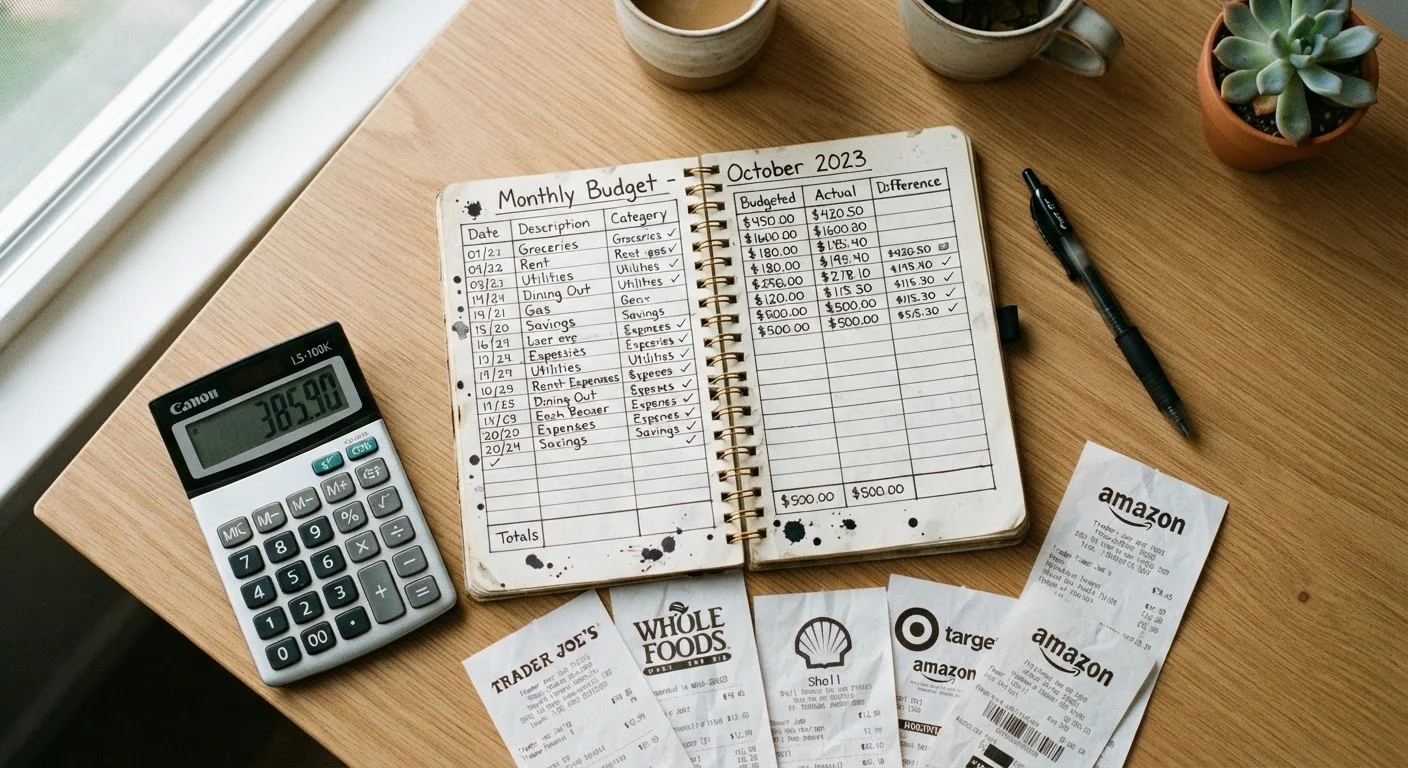
Photo credit: readerspanel.com
In this article
Most budgets split costs into fixed and variable, but many expenses don't fit neatly. Learn how to categorize spending more accurately.
Key Takeaways
- Fixed and variable are starting points, not a complete budgeting system.
- Many costs are semi-fixed: they change, but only occasionally and within a narrow range.
- Irregular expenses such as car registration or annual subscriptions need a separate planning approach.
- Misclassifying expenses causes budget gaps that look random but are actually predictable.
- Treating categories as fluid rather than rigid makes a budget more accurate over time.
Why the two-category model breaks down
The fixed-versus-variable framework gives budgets a starting structure, and that is genuinely useful. Fixed costs tell you what you owe no matter what happens in a given month. Variable costs tell you where you have room to adjust. But the model assumes a cleaner division than most household budgets actually have.
Consider a car insurance premium. It is the same amount every six months, but not every month. Between renewals, it behaves like a fixed cost. At renewal, the insurer may adjust the rate, so the amount is not truly locked in permanently. Calling it fixed is mostly accurate but incomplete.
Utilities create a similar problem. A winter heating bill in Minnesota is not the same as a July one. The cost is variable by season, but within each season it tracks a predictable pattern. Budgeting the same flat monthly number year-round will leave you short in January and holding unplanned surplus in May.
The core issue is that fixed and variable describe the behavior of a cost, not a permanent characteristic of it. Most costs shift their behavior depending on the time window you examine.
Fixed does not mean permanent
A cost can be fixed for several months and then change, such as when a lease renews at a higher rent or an insurer adjusts a premium. The label 'fixed' describes short-term predictability, not a guarantee that the amount will never change. Reviewing your fixed-cost list annually catches changes before they quietly distort your budget.
A more useful way to think about expense categories
Adding one or two intermediate categories makes a budget significantly more accurate without making it complicated.
Semi-fixed expenses
These costs are stable for extended periods but change occasionally. Internet service, gym memberships, and streaming bundles often reprice once a year or when you change a plan. They are not fixed forever, but they are not month-to-month variables either. Reviewing them once or twice a year is the right cadence, not monthly.
Periodic or irregular expenses
These are predictable in that they will happen, but they do not appear on a monthly cycle. Car registration, annual software subscriptions, and professional dues fall here. The quiet budget damage these costs cause comes from treating them as surprises when they are actually foreseeable. Dividing the annual total by 12 and setting that amount aside monthly converts them into manageable line items.
Semi-variable expenses
These change monthly but within a bounded range. Groceries for a household of four will not triple from month to month, even though the exact amount shifts. Setting a realistic range rather than a single number is more honest and usually more useful than one average figure.
Expenses that commonly end up in the wrong bucket
Misclassification is where budget gaps originate. A few categories that routinely get mislabeled:
- Subscriptions: Monthly subscriptions look fixed but accumulate quietly. Annual subscriptions paid as a lump sum are periodic costs that get forgotten until the charge lands.
- Car expenses: Gas is variable. Insurance is semi-fixed. Registration is periodic. Grouping them all under one vague "car" category obscures which part of the budget needs attention. The full cost of car ownership spans all three expense types.
- Groceries: These feel variable but often cluster in a tight range for a given household. Treating them as completely unpredictable prevents meaningful planning.
- Utilities: As noted above, utilities have a seasonal shape. A flat monthly estimate ignores that shape.
Spending categories reveal patterns only when they are specific enough to be meaningful. Broad buckets hide the information you need to make adjustments.
Map each expense to a review frequency
Instead of just labeling a cost fixed or variable, also note how often it needs to be checked. Truly fixed costs like a mortgage need attention only when the loan terms change. Semi-fixed costs like subscriptions need a quick review once or twice a year. Periodic costs need a calendar reminder set ahead of each due date. That extra column in your budget sheet prevents most classification-related surprises.
Putting more accurate categories to work
Reclassifying expenses does not require a new budgeting app or a complete overhaul. Three practical steps make a real difference.
First, go through the last 12 months of bank and credit card statements and flag every non-monthly charge. Group them by approximate annual total and divide by 12. That monthly equivalent goes into a dedicated savings line item, not into your regular expense columns.
Second, separate semi-fixed costs from truly fixed ones and set a calendar reminder to review them at renewal. When a service reprices, the change does not catch you mid-month with a number that no longer matches your budget.
Third, use a range for semi-variable costs rather than a single number. A grocery budget noted as a range gives you a realistic ceiling and a meaningful floor, which makes it easier to notice when spending drifts outside the pattern.
If your income is already stretched, budgeting approaches focused on stability first address how to sequence these changes without adding financial stress. For a full annual view of household costs, the home expense checklist walks through categories room by room.
This article is for general informational purposes only and does not constitute personalized financial advice. Consult a qualified financial professional for guidance specific to your situation.
Frequently Asked Questions
Author
Smart Shopping Editorial Team
Smart Shopping Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →