
Savings Goals That Actually Stick: Lessons From Behavioral Finance
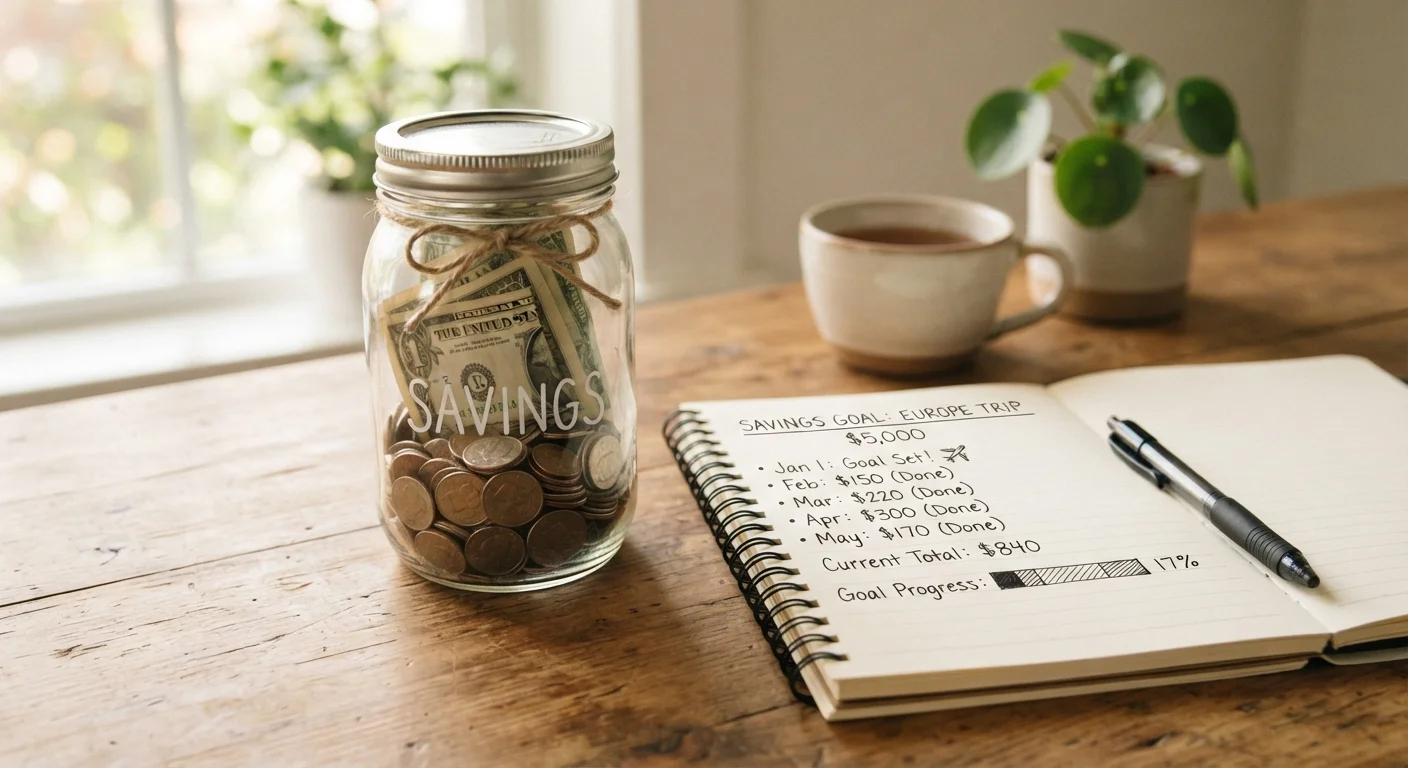
Photo credit: readerspanel.com
In this article
Why most savings goals quietly fail, and what research in behavioral finance suggests about setting ones that hold up over time.
Key Takeaways
- Vague savings goals fail more often than specific, time-bound ones because the brain has nothing concrete to act on.
- Behavioral finance research shows that automating transfers removes the willpower requirement entirely.
- Mental accounting, where you label money by purpose, makes savings feel more protected from spending impulses.
- Progress visibility, such as a simple tracker, increases follow-through on savings goals.
- Tying a goal to a concrete event or deadline produces stronger commitment than an open-ended intention.
Why good intentions are not enough
Most people who fail to save consistently are not irresponsible. They set goals sincerely, then watch those goals fade by the second month. Behavioral finance, the study of how psychology shapes financial decisions, offers a more useful explanation than willpower: the architecture of the goal itself determines whether it survives contact with real life.
A goal like "save more this year" gives the brain no anchor. There is no trigger, no finish line, and no way to measure progress. Without those elements, the goal competes daily against immediate spending and almost always loses. The fix is not more discipline; it is better goal design.
For a broader foundation on where savings fits in a financial plan, see the starter's roadmap to personal saving.
The behavioral principles that change outcomes
Several well-documented effects in behavioral finance explain why certain savings strategies hold up while others collapse. Understanding them helps you build goals that work with your psychology rather than against it.
Attach a specific dollar amount and deadline to every savings goal
Research on goal-setting consistently finds that concrete, measurable targets produce higher completion rates than abstract intentions. A defined endpoint also lets you calculate exactly how much to set aside each pay period, turning a vague wish into an arithmetic problem.
Use labeled, separate accounts for distinct savings goals
Mental accounting is a documented tendency to treat money differently depending on how it is categorized. Giving each goal its own account or sub-account makes that money psychologically harder to spend on something else, even when the balances are technically accessible.
Automate transfers to move money before you can spend it
Present bias, the tendency to overweight immediate rewards against future ones, is the primary reason well-intentioned savers spend money before saving it. Automating a transfer on payday removes the decision entirely, sidestepping the bias rather than trying to override it.
Track progress visibly, even with a simple method
Seeing a goal advance creates a documented motivational effect sometimes called the 'goal gradient': effort tends to increase as completion approaches. A visible record also surfaces early if saving has stalled, allowing a course correction before the goal is abandoned.
Build in a small, planned reward at meaningful milestones
Long timelines suppress motivation because the payoff feels abstract. A small intermediate reward recalibrates the timeline so the brain sees a near-term benefit, which sustains behavior over months or years.
One companion issue worth understanding is how rising income can silently erode savings through spending expansion. The dynamics of lifestyle creep are worth reading alongside these practices.
Putting the system together
Individual principles are more useful when combined into a single, low-maintenance system. The core move is removing as many active decisions as possible. Each time saving requires a conscious choice, there is an opportunity to skip it.
Automation is the most reliable way to eliminate that friction. A step-by-step setup for automating transfers walks through the mechanics of linking accounts and scheduling deposits so saving happens before spending gets a chance.
It is also worth matching where you keep savings to how soon you will need them. Aligning money to your financial timeline prevents the common mistake of keeping long-term savings in low-yield accounts. For a plain-language explanation of what your savings actually earn, understanding APY is a good next step.
This article is for general informational purposes only and does not constitute personalized financial advice. Consider consulting a licensed financial professional for guidance specific to your situation.

Author
Personal Finance Editorial Team
Personal Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →