
Cash vs. Card Spending: How Your Payment Method Shapes Your Budget Behavior
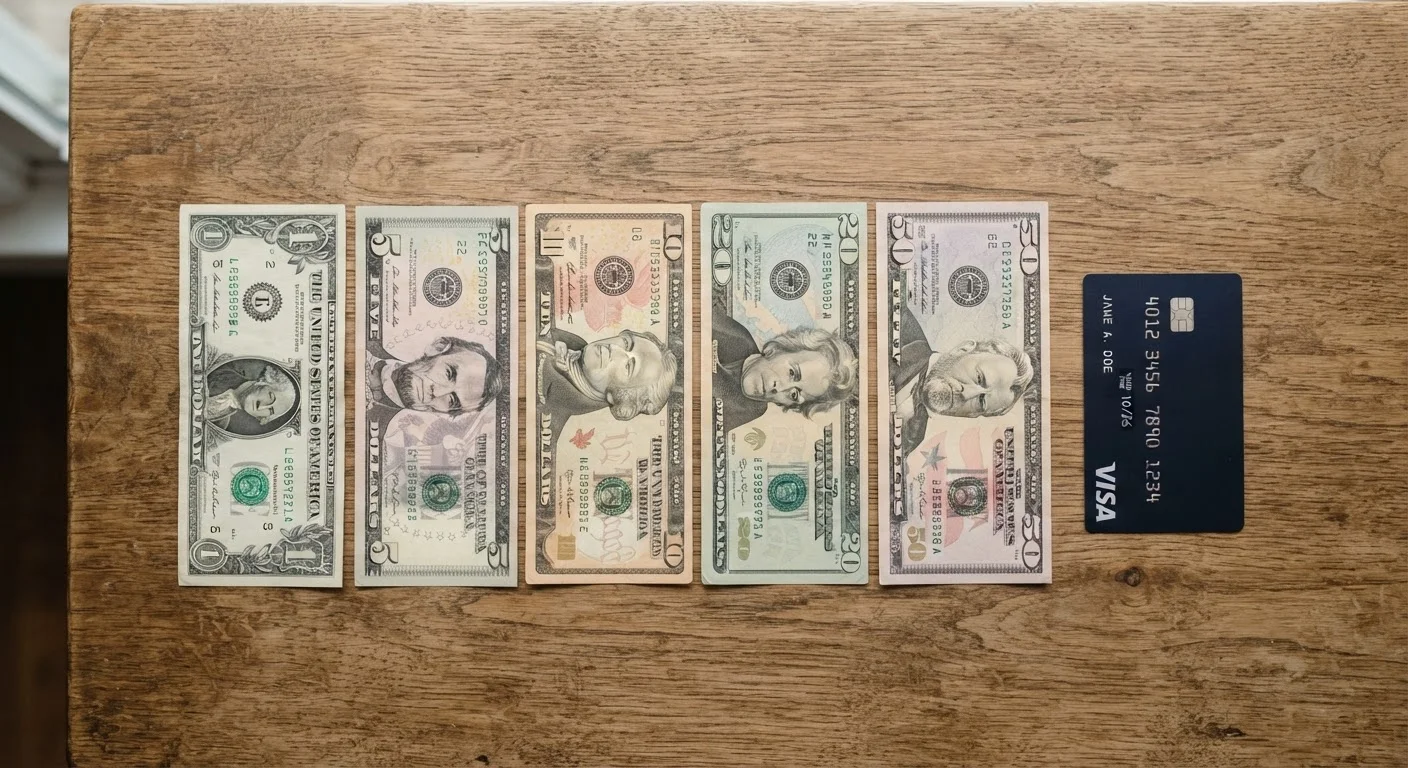
Photo credit: readerspanel.com
In this article
Research suggests the way you pay can influence how much you spend. A balanced look at cash and card habits and what they mean for sticking to a budget.
Why payment method affects spending
The way you pay is not just a mechanical detail. Behavioral research, including work from consumer psychologists at MIT and Carnegie Mellon University, has found that paying with cash tends to feel more painful than swiping a card. This friction, sometimes called the "pain of paying," can slow down spending. When you hand over physical bills, the transaction feels final in a way that tapping a card does not.
Cards, especially contactless ones, compress the mental gap between wanting something and getting it. That compression is convenient, but it can also make it easier to spend past what you planned. This does not mean cards are harmful by default. It means the psychology around them works differently, and a budget that ignores that difference may be harder to stick to.
See also: why overspending happens even with a budget in place.
| Cash | Card | |
|---|---|---|
| Spending friction | High: physical handover slows decisions | Low: tap or swipe is nearly frictionless |
| Fraud protection | None: lost cash is unrecoverable | Strong: disputes and liability limits apply |
| Spending records | Manual only: receipts or self-logging required | Automatic: full statement history available |
| Budget enforcement | Hard cap: physically limited by what you carry | Soft cap: relies on self-monitoring or alerts |
| Interest risk | None | Present if balance is not paid in full |
| Online purchases | Not accepted for most digital transactions | Works for online, recurring, and in-person |
| Rewards | None | Available on many cards, value varies |
What cash does well and where it falls short
Cash works as a natural cap. If you pull out $200 for groceries each week and spend it, you are done. There is no overdraft, no interest, and no reconciling a statement later. For people who struggle with variable discretionary categories, this hard limit can be more effective than any app or spreadsheet.
The drawbacks are practical. Cash offers no fraud protection. If it is lost or stolen, it is gone. It also produces no automatic record, so unless you save receipts or log purchases manually, your spending history disappears. Cash is also less accepted for online purchases and subscriptions, which now make up a large share of most household budgets.
Matching cash to your highest-risk categories
Before switching entirely to cash, pull three months of card statements and find the two or three categories where you most often exceed your plan. Assign a cash envelope only to those. This is more manageable than an all-cash system and targets the actual problem areas in your budget.
What cards do well and where they fall short
Cards generate a complete transaction record, which makes them useful if you track spending through a budgeting app or bank statement. Most cards also carry fraud liability protections that cash cannot offer: if an unauthorized charge appears, you can dispute it. Some cards provide purchase protection, extended warranty coverage, or travel benefits.
The risk with cards is well documented. When spending does not feel immediate, it is easier to exceed a budget without noticing. Interest charges on unpaid balances can outweigh any rewards earned. A card that earns 2% cash back while carrying a 20% APR balance is a net financial loss. Reading your spending categories carefully can help you catch this pattern before it compounds.
Hybrid approaches and how to build one
Many personal finance educators suggest using cash for categories where you tend to overspend, particularly dining out, entertainment, and clothing, while keeping cards for fixed or predictable expenses like utility bills, subscriptions, and travel. This splits the benefit of each method by category rather than forcing a single rule across all spending.
To build a hybrid system, start by identifying which categories in your budget most often run over. Assign a weekly or monthly cash envelope to those categories. Use a card for everything else, and set up automatic full-balance payments to avoid interest. The budgeting basics hub has more on structuring a workable spending plan around this kind of category logic.
If you are deciding between percentage-based and dollar-amount limits for each category, comparing those two approaches is a useful next step.
This article is for informational purposes only and does not constitute financial advice. For guidance on your specific financial situation, consult a qualified financial professional.
Author
Smart Shopping Editorial Team
Smart Shopping Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →