
What Factors Actually Determine Your Car Insurance Premium
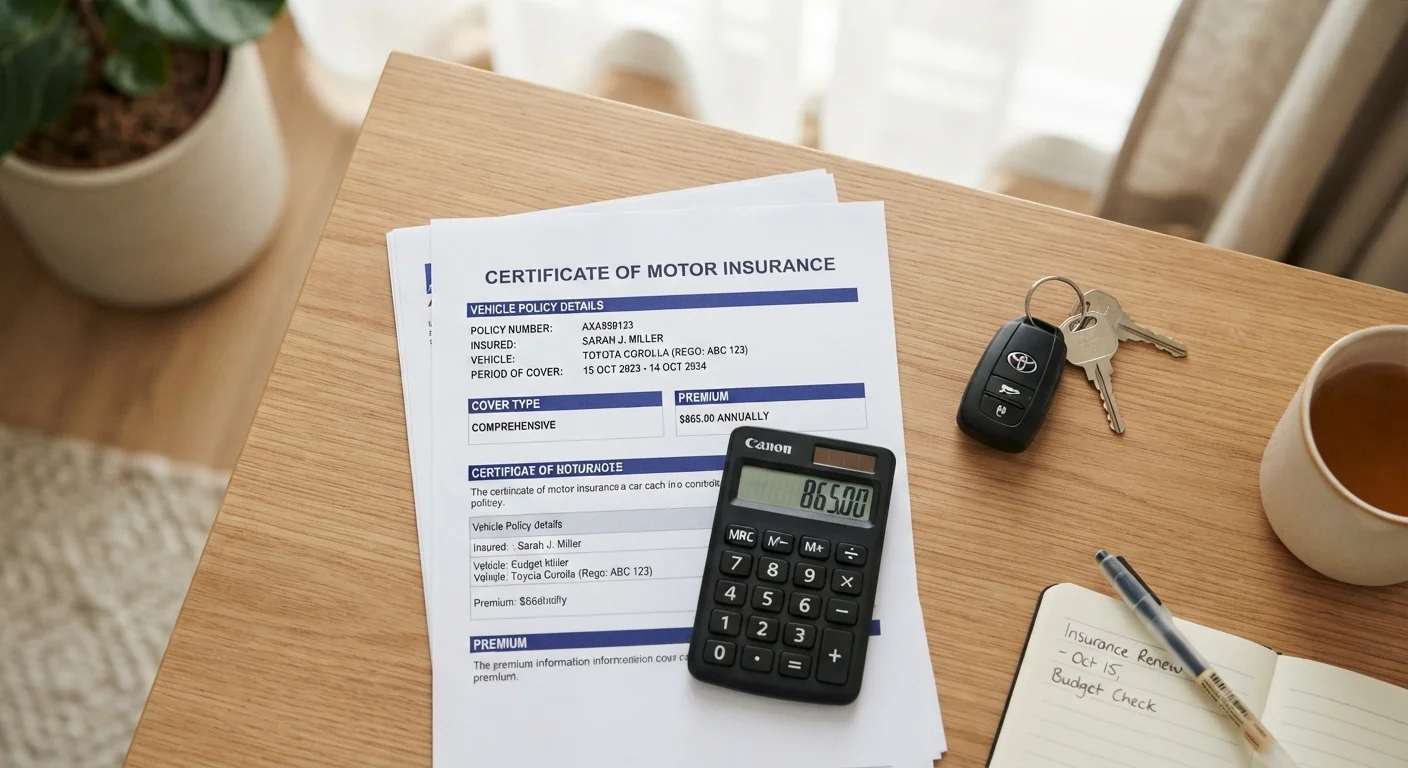
Photo credit: readerspanel.com
Age, location, credit history, and driving record all play a role in your rate. Here's how insurers calculate what you pay and why.
How insurers arrive at your rate
Car insurance premiums are not random. Insurers use actuarial data to estimate the probability that a given driver will file a claim, then price the policy accordingly. The result is a rate built from a stack of individual risk factors, each weighted differently by different carriers. Understanding those factors does not guarantee a lower bill, but it clarifies where your money goes and which variables are actually within your control.
For a plain-language foundation on coverage types and policy structure, see the Car Insurance 101 guide before working through the rate factors below.
Driver-specific factors
Age and driving experience. Statistically, new drivers and teenagers file more claims than experienced middle-aged drivers. Rates typically drop through a driver's twenties and thirties, then can rise again for drivers in their late seventies, reflecting elevated accident rates at both ends of the age spectrum.
Driving record. At-fault accidents, speeding tickets, and serious violations such as a DUI will raise your premium. Most carriers look back three to five years on your motor vehicle report. A clean record over that window is one of the most direct ways to keep rates lower.
Annual mileage. The more miles you drive, the more exposure you have to an accident. Many insurers ask for an estimated annual mileage figure at application. Low-mileage drivers may qualify for reduced rates in some states. The relationship between mileage and total ownership cost is examined in more detail in the mileage and car ownership costs article.
Credit-based insurance score. In most states, insurers use a version of your credit history, called a credit-based insurance score, to predict claim likelihood. This is separate from a standard credit score but is calculated from similar data: payment history, outstanding balances, and account age. A handful of states, including California, Hawaii, and Massachusetts, prohibit or restrict this practice.
Actuarial data
Statistical records used by insurers to estimate the likelihood and cost of future claims. Actuaries analyze large populations of drivers to assign risk probabilities to individual characteristics.
Credit-based insurance score
A score derived from credit history data that some insurers use to predict how likely a policyholder is to file a claim. It differs from a standard credit score and is prohibited in some states.
Comprehensive coverage
An optional coverage type that pays for vehicle damage caused by events other than a collision, such as theft, weather, or fire.
Deductible
The dollar amount a policyholder pays out of pocket before insurance covers the remaining cost of a covered claim. A higher deductible generally produces a lower monthly or annual premium.
Motor vehicle report (MVR)
An official record from your state's licensing authority that lists your driving history, including violations and accidents. Insurers typically pull this at the time of application and renewal.
Liability coverage
Coverage that pays for bodily injury and property damage you cause to others in an at-fault accident. Most states require a minimum level of liability coverage to register a vehicle.
Vehicle and location factors
The vehicle itself. Insurers consider the cost to repair or replace a vehicle, its safety ratings, and its historical theft rate. A car with expensive parts or a high theft frequency will generally cost more to insure for comprehensive and collision coverage. Safety technology that reduces injury severity can work in your favor on injury-related coverages.
Where you live. Your ZIP code affects your rate through several channels: local accident frequency, vehicle theft rates, weather-related claim history, and the density of traffic around you. Urban drivers typically pay more than rural drivers in the same state. State-level variation is significant too; insurance regulations, minimum coverage requirements, and claim costs differ across the country. The state-by-state differences in car ownership expenses article covers how geography shapes what you pay across multiple cost categories.
Coverage levels and deductibles. The coverages you select and the deductibles you choose directly affect your premium. A lower deductible shifts more financial risk to the insurer, which means a higher premium. Carrying only state-required minimums costs less upfront but leaves more financial exposure after a serious accident.
This article is for general informational purposes only and does not constitute personalized financial or insurance advice. Consult a licensed insurance professional for guidance specific to your situation.
Author
Automotive Life Editorial Team
Automotive Life Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →