
Car Insurance 101: What Every Driver Needs to Understand
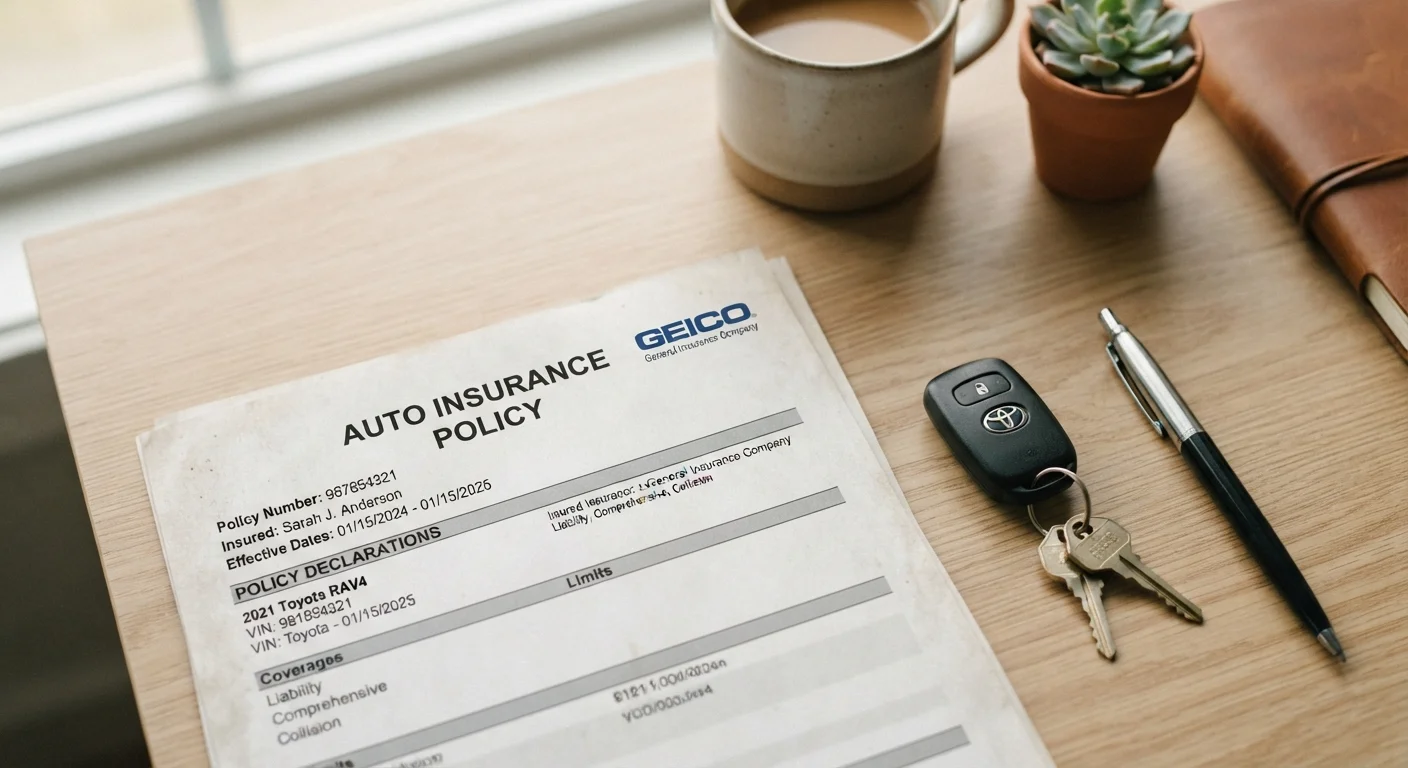
Photo credit: readerspanel.com
In this article
Coverage types, deductibles, liability limits: a plain-language guide to understanding your auto insurance policy before you need to use it.
Key Takeaways
- Every U.S. state except New Hampshire requires drivers to carry at least a minimum level of liability coverage.
- Liability, collision, and comprehensive are distinct coverage types that protect against different events.
- Your deductible is the amount you pay out of pocket before insurance covers a claim.
- Several personal and vehicle factors influence your premium, many of which you can control over time.
- The declarations page is the single most useful summary of what your policy actually covers.
Why car insurance works the way it does
Car insurance is a contract between you and an insurer. You pay a premium; the insurer agrees to cover specific financial losses up to defined limits. The system exists because car accidents can create costs that most individuals cannot absorb alone, from medical bills to vehicle repairs to legal judgments.
Every state except New Hampshire requires drivers to carry at least liability insurance, which protects other people when you cause an accident. New Hampshire still holds drivers financially responsible for damages they cause, so the practical obligation exists there as well. Beyond that state minimum floor, how much coverage you carry is largely a financial decision shaped by your vehicle's value, your assets, and your tolerance for out-of-pocket risk.
If you are also thinking through the full financial picture of owning a vehicle, the car ownership cost audit covers how insurance fits alongside fuel, maintenance, and registration.
Liability coverage
Pays for injuries or property damage you cause to others in an accident. It does not cover your own vehicle or injuries.
Collision coverage
Pays to repair or replace your vehicle after a crash with another car or object, no matter who caused it.
Comprehensive coverage
Covers damage to your vehicle from non-collision events such as theft, fire, flooding, or hail.
Deductible
The fixed amount you pay out of pocket on a covered claim before your insurer pays the remainder.
Premium
The amount you pay periodically to keep your insurance policy active, billed monthly, semi-annually, or annually.
Coverage limit
The maximum dollar amount your insurer will pay for a single covered loss or per policy period.
Declarations page
A summary page at the front of your policy listing your vehicles, drivers, coverage types, limits, and deductibles.
Uninsured motorist coverage
Protects you when an at-fault driver has no insurance or carries limits too low to cover your losses.
The main coverage types explained
Liability coverage has two parts: bodily injury liability, which pays for injuries to others when you are at fault, and property damage liability, which covers damage you cause to someone else's vehicle or property. Limits are written as three numbers, such as 25/50/25, meaning $25,000 per injured person, $50,000 per accident, and $25,000 for property damage.
Collision coverage pays to repair or replace your own vehicle after a crash with another car or a stationary object, regardless of fault. Comprehensive coverage handles vehicle damage from events outside a collision: theft, fire, hail, flooding, vandalism, and animal strikes. Lenders and leasing companies typically require both.
Uninsured and underinsured motorist coverage steps in when the at-fault driver either has no insurance or carries limits too low to cover your losses. Medical payments coverage (MedPay) or personal injury protection (PIP, required in some no-fault states) covers medical costs for you and your passengers regardless of fault.
For a deeper look at terms that often appear on policy documents, see commonly misunderstood car insurance terms.
Deductibles, limits, and premiums
Your deductible is the portion of a covered claim you pay before the insurer pays the rest. A $500 deductible on a $3,000 repair means you pay $500 and the insurer pays $2,500. Choosing a higher deductible lowers your premium; choosing a lower one raises it. The right balance depends on what you could realistically afford after an accident without financial hardship.
Your coverage limit is the maximum the insurer will pay for a covered loss. Liability limits below your net worth can leave you personally exposed if a serious accident produces damages above that ceiling. Umbrella policies can extend that ceiling, though they are a separate product.
Your premium is what you pay for the policy, billed monthly, semi-annually, or annually. It reflects the insurer's assessment of how likely you are to file a claim and how costly that claim might be.
State minimums may not be enough
Meeting your state's minimum liability requirement keeps you legal, but those minimums are often set low and may not cover the full cost of a serious accident. If a judgment against you exceeds your liability limits, you are personally responsible for the difference. Consider whether your limits reflect the value of your assets and your realistic exposure.
What affects your premium
Insurers use a range of factors to calculate your rate. Driving history carries significant weight: at-fault accidents and moving violations generally push premiums up, while a clean record over time tends to bring them down. Years of driving experience and age also factor in, with newer drivers typically paying more.
The vehicle itself matters. A car with high repair costs, a poor safety rating, or a history of theft claims in its model category will generally cost more to insure. Annual mileage, where you garage the car, and whether it is used for commuting or personal trips all influence the calculation as well.
Credit history is a rating factor in most states, though a few states prohibit its use. Your chosen coverage levels and deductibles also directly affect the final number. None of these factors guarantee a specific rate; insurers weigh them differently.
How to read your declarations page
The declarations page (often called the dec page) is the summary at the front of every policy. It lists the policy period, insured vehicles by VIN, named drivers, each coverage type you carry, the limit for each, and the deductible for each applicable coverage. It also shows the premium breakdown by coverage.
Reading it carefully before you need to file a claim tells you whether you have collision, whether your limits are adequate, and whether all drivers in your household are listed. Unlisted drivers may not be covered, depending on your policy's terms.
If your vehicle is financed, the dec page will also show your lender as a lienholder, confirming they have a financial interest in the comprehensive and collision coverage. If you want to understand how your loan terms connect to your insurance obligations, auto financing key terms explains the relationship.
Filing a claim: what actually happens
After an accident or covered loss, you notify your insurer by phone or through their app or website. You provide basic information about what happened, when, where, and who was involved. For accidents with another driver, exchange insurance and contact information at the scene.
The insurer assigns an adjuster to evaluate the damage and determine the payout. For vehicle repairs, the adjuster may inspect the car in person or remotely using photos. The insurer pays the repair shop directly or issues a check to you, minus your deductible.
For bodily injury claims, the process can take considerably longer, particularly if liability is disputed. Keeping records, including a police report number, photos, and contact details for witnesses, strengthens your position regardless of who was at fault.
Filing a claim may affect your premium at renewal. For minor damage close to your deductible, it may be worth calculating whether paying out of pocket is more cost-effective than the potential rate increase. As a new driver navigating all the responsibilities of vehicle ownership, the first-time car owner maintenance guide covers how maintenance habits can also influence long-term costs.
This article is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage requirements vary by state and individual circumstance. Consult a licensed insurance professional for guidance specific to your situation.
Frequently Asked Questions
Author
Automotive Life Editorial Team
Automotive Life Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →