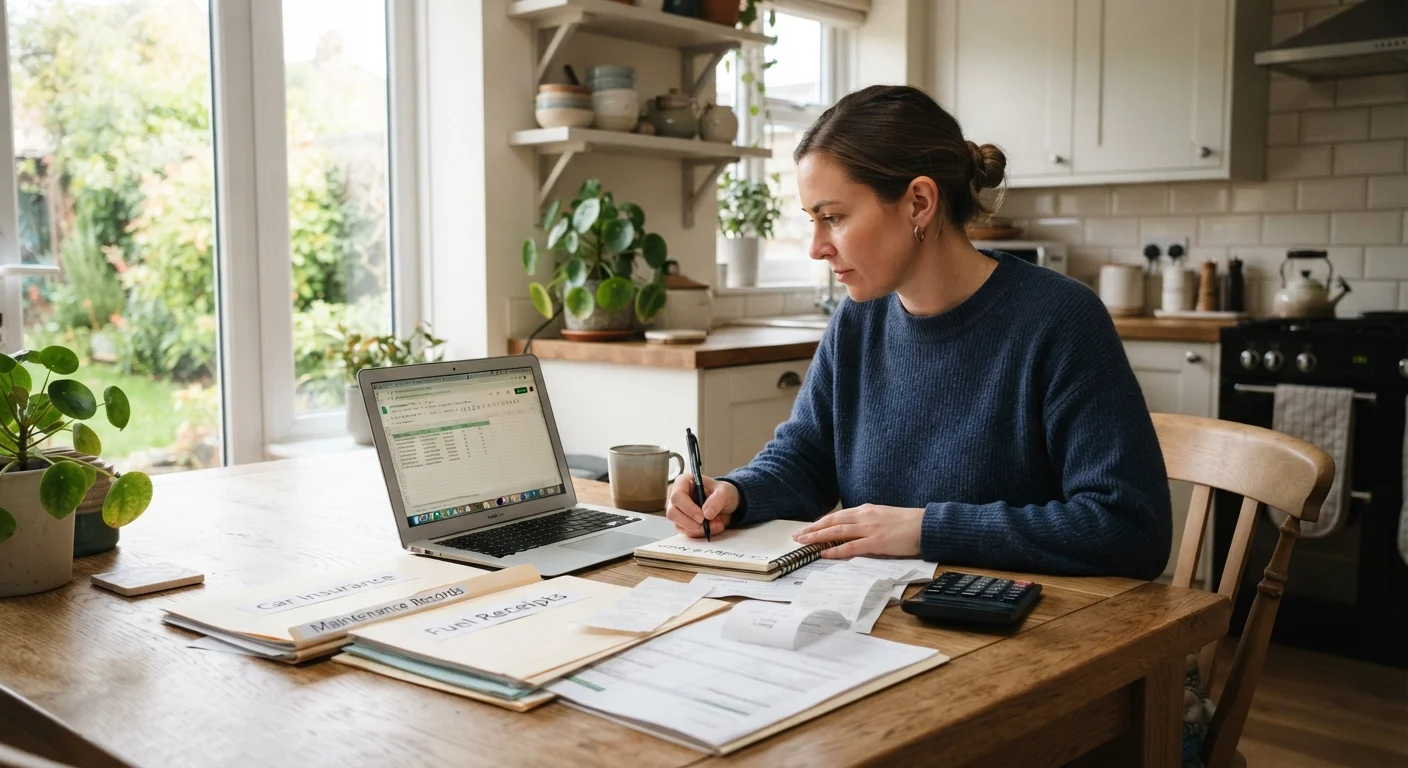
Use this checklist to account for every expense tied to your vehicle, from insurance and registration to fuel and unexpected repairs.
Why an annual cost audit matters
A car payment is one line item. The full cost of owning a vehicle is something else. Registration, fuel, insurance, oil changes, tires, unexpected repairs, and parking fees all add up across the year, often without any single moment that makes the total obvious. Drivers who track these costs are better positioned to decide when to repair versus replace, how much emergency savings to keep, and whether their current vehicle still fits their budget. The most common budget errors come from treating infrequent costs as surprises rather than predictable line items.
This checklist is organized into four categories: fixed costs, variable costs, maintenance, and financial review. Work through each group once a year, ideally before you renew insurance or file taxes.
Required
12 months of bank or credit card statements
Used to total fuel, maintenance, parking, and other vehicle-related spending accurately.
Required
Vehicle owner's manual
Lists scheduled maintenance intervals and fluid specifications so you can identify upcoming services.
Required
Current insurance declarations page
Shows your premium, coverage types, deductible, and policy limits for review and comparison.
Required
Registration renewal notice
Confirms your annual registration fee and any associated state inspection requirement.
Required
NHTSA VIN lookup tool (nhtsa.gov)
Checks your vehicle identification number for any open federal safety recalls.
Required
Spreadsheet or notepad
Records totals from each category so you can calculate an annual and monthly ownership cost.
The cost audit checklist
Gather your insurance declarations page, last twelve months of bank or credit card statements, your vehicle registration renewal notice, and any repair receipts. A spreadsheet or even a single sheet of paper is enough to record totals.
Fixed costs
Record your annual insurance premium by pulling the declarations page from your current policy. Note the coverage types and deductible so you can compare them when you shop next renewal.Must
Write down your annual registration fee and any state-required inspection fee. These are predictable, so add them to a savings line in your monthly budget.Must
If you carry an auto loan, confirm the remaining balance, monthly payment, and payoff date. Note any prepayment options.Must
Check whether you pay for any vehicle-related subscriptions, such as connected-car services, roadside assistance plans, or extended warranties. Cancel any you do not use.Should
Variable costs
Total your fuel spending for the past 12 months using bank or credit card statements. Divide by your estimated annual mileage to get a rough cost-per-mile figure.Must
Review whether your actual fuel economy has changed from what you expected when you bought the vehicle. A noticeable drop can signal a maintenance issue worth investigating.Should
Add up parking and tolls paid over the year. These are easy to overlook but can be a meaningful monthly expense for urban or commuter drivers.Should
Note any car-wash or detailing costs. These are discretionary, but knowing the annual total helps you decide whether a different approach makes sense.Nice to have
Maintenance and repairs
List every maintenance service completed in the past year, including oil changes, tire rotations, and fluid top-offs, with the cost of each.Must
Check your owner's manual for services due in the next 12 months based on mileage or time intervals. Estimate costs so you can set aside funds in advance.Must
Review tire condition and age. Tires older than six years may need replacement regardless of tread depth; plan for that cost if replacement is approaching.Must
Note any repairs completed this year and flag any deferred repairs still outstanding. Deferred work often costs more when addressed later. The connection between routine upkeep and repair costs is worth understanding before skipping a service.Must
Check the status of overlooked items like spark plugs, the engine air filter, and cabin air filter. These parts degrade quietly and are inexpensive when replaced on schedule.Should
Confirm whether your vehicle has any open safety recalls by checking the National Highway Traffic Safety Administration (NHTSA) recall database using your VIN. Recall repairs are typically done at no cost at a dealership.Must
Financial review
Add all categories to produce a total annual ownership cost, then calculate a monthly average. Compare this against any budget you set at the start of the year.Must
Assess whether your emergency fund covers at least one major unexpected repair, generally $1,000 to $3,000 depending on vehicle age and type. Adjust your savings target if it does not.Must
Review your insurance policy for coverage gaps or redundancies. If your vehicle's market value has dropped significantly, reconsider whether comprehensive and collision coverage still makes financial sense given your deductible.Should
If your vehicle is more than seven years old, research its current market value using publicly available valuation tools. This gives context for repair decisions and informs any trade-in or sale planning.Should
Note the gap between what you pay annually and what a comparable newer or more fuel-efficient vehicle would cost. This is not a reason to replace automatically, but it is useful data for longer-term planning. A full comparison of new versus used ownership costs can frame that decision more clearly.Nice to have
Once every category has a number, add them for an annual figure, then divide by 12 for a monthly average. Compare that number against what you budgeted or assumed. If the gap is significant, building a realistic monthly car budget from scratch is often more accurate than adjusting an old estimate.
Review your insurance coverage separately. Confirm that your liability limits, deductible, and optional coverages still match your situation. If you are uncertain what terms like collision, comprehensive, or gap coverage mean, a plain-language insurance guide can help before you call your insurer.
If your vehicle is aging, factor in the larger scheduled services that appear after 60,000 or 100,000 miles. Timing belt replacement, transmission service, and brake work are covered in detail in a breakdown of deferred ownership costs. Drivers weighing whether to keep an older vehicle or trade it in will find a balanced financial comparison in the trade-off analysis for keeping vs. trading.
This audit also fits naturally into a broader household review. The annual home expense checklist covers other predictable categories worth revisiting at the same time.
This article is for general informational purposes only and does not constitute financial or legal advice. Consult a qualified financial professional for guidance specific to your situation.
Author
Automotive Life Editorial Team
Automotive Life Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
All published content on this website is for informational and educational purposes only and should not be taken as professional advice. We recommend that readers seek expert opinion before making any decisions. The website is not responsible for any actions taken based on the information provided on this website. We are not liable for any inaccuracies, modifications, or omissions in information. Moreover, external links or third-party content are provided for convenience; we are not liable for their correctness. Users are advised to verify every piece of information before they use it for any purpose.