
Keeping a Car Longer vs. Trading It In: The Financial Trade-offs
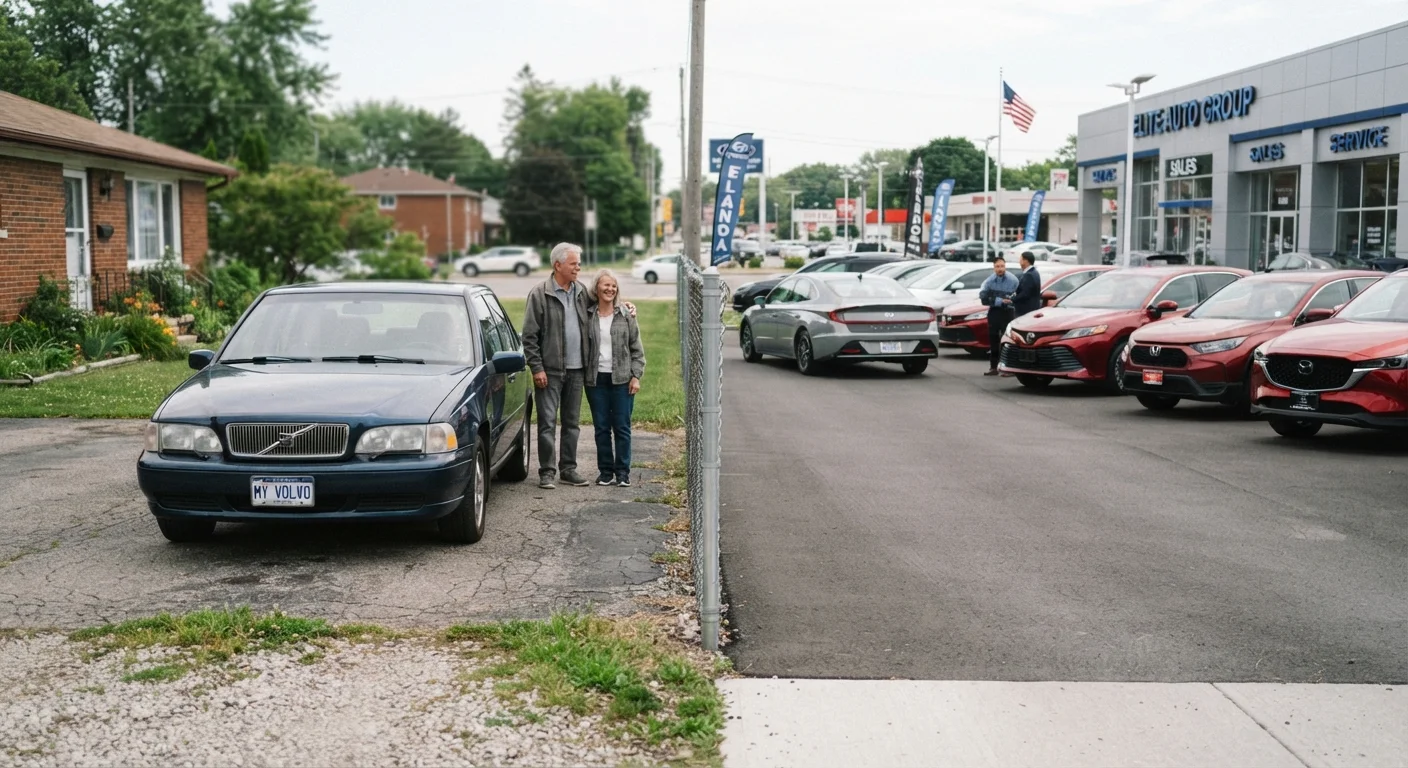
Photo credit: readerspanel.com
In this article
There's no universal right answer on when to replace a vehicle. Here's a balanced look at the financial reasoning on both sides.
Key Takeaways
- Keeping a paid-off car typically costs less per month than financing a newer one.
- Older vehicles often carry higher repair risk but lower insurance premiums.
- Depreciation hits hardest in the first few years, which benefits long-term owners.
- A thorough cost audit helps compare real ownership expenses on both sides.
- Neither choice is automatically better: the math depends on your specific vehicle and finances.
No monthly loan payment once the car is paid off
Eliminating a car payment frees up cash that would otherwise go toward principal and interest. That difference can be hundreds of dollars a month depending on the loan amount and term.
Depreciation no longer works against you
New vehicles lose a significant share of their value in the first few years of ownership. Once a car has passed that window, its market value stabilizes, and you absorb less loss over time.
Insurance premiums tend to drop on older vehicles
Lenders typically require comprehensive and collision coverage on financed cars. Once a vehicle is owned outright and has lower market value, many drivers adjust coverage levels, which can reduce premiums.
Maintenance history is known and documented
When you have owned a car for years, you know what has been serviced, replaced, and repaired. That history is useful for anticipating upcoming costs and avoiding surprises.
Repair costs increase as vehicles age
Wear items like timing belts, water pumps, and transmissions eventually need attention. The costs that arrive later in a vehicle's life are often underestimated by owners focused only on routine maintenance.
Fuel efficiency may lag newer options
Older powertrains generally consume more fuel than current equivalents. Over high annual mileage, that gap adds up, and it is worth factoring into any comparison against a newer vehicle.
Safety technology gaps widen over time
Automatic emergency braking, lane-keeping assist, and blind-spot monitoring have become standard on newer vehicles. Older cars may lack these features entirely, which is a legitimate consideration beyond finances.
Reliability becomes harder to predict
Even a well-maintained older vehicle carries more uncertainty than a newer one under warranty. A single major failure, such as a transmission or engine issue, can shift the financial calculation quickly.
Why this decision is rarely straightforward
Most advice on this topic defaults to a simple rule: keep the car as long as it runs. That misses the real question, which is whether the total cost of keeping it compares favorably to the total cost of replacing it. The answer depends on factors that vary widely between drivers and vehicles.
A practical ownership cost audit is the most useful starting point. It forces you to count every line item, including insurance, fuel, registration, and repair history, rather than estimating from memory.
Ownership costs do not follow a straight line. They tend to be high in the first year (purchase price, taxes, initial registration), lower in the middle years, and then rise again as components wear out. Trading in during the low-cost middle period often means absorbing a new set of early-stage costs on the replacement vehicle.
The case for keeping your current vehicle
No monthly loan payment once the car is paid off
Eliminating a car payment frees up cash that would otherwise go toward principal and interest. That difference can be hundreds of dollars a month depending on the loan amount and term.
Depreciation no longer works against you
New vehicles lose a significant share of their value in the first few years of ownership. Once a car has passed that window, its market value stabilizes, and you absorb less loss over time.
Insurance premiums tend to drop on older vehicles
Lenders typically require comprehensive and collision coverage on financed cars. Once a vehicle is owned outright and has lower market value, many drivers adjust coverage levels, which can reduce premiums.
Maintenance history is known and documented
When you have owned a car for years, you know what has been serviced, replaced, and repaired. That history is useful for anticipating upcoming costs and avoiding surprises.
The strongest argument for keeping a paid-off car is that the monthly cost floor drops substantially. Even with repair bills factored in, many owners find that their annual spending on an older vehicle stays below what a new loan payment alone would cost.
Depreciation is the other major factor. New vehicles, and even late-model used ones, lose value quickly. Owners who hold a car past the steep part of that curve avoid absorbing those losses. The long-term cost comparison between vehicle types shows how this plays out differently depending on powertrain choice, but the depreciation dynamic applies broadly.
The case for trading in
Repair costs increase as vehicles age
Wear items like timing belts, water pumps, and transmissions eventually need attention. The costs that arrive later in a vehicle's life are often underestimated by owners focused only on routine maintenance.
Fuel efficiency may lag newer options
Older powertrains generally consume more fuel than current equivalents. Over high annual mileage, that gap adds up, and it is worth factoring into any comparison against a newer vehicle.
Safety technology gaps widen over time
Automatic emergency braking, lane-keeping assist, and blind-spot monitoring have become standard on newer vehicles. Older cars may lack these features entirely, which is a legitimate consideration beyond finances.
Reliability becomes harder to predict
Even a well-maintained older vehicle carries more uncertainty than a newer one under warranty. A single major failure, such as a transmission or engine issue, can shift the financial calculation quickly.
The financial argument for trading in gets stronger when repair costs become frequent or unpredictable. A single $3,000 transmission repair does not automatically justify a new car, but a pattern of $1,500 to $2,500 repairs across consecutive years starts to look different against a loan payment that also comes with a warranty.
Fuel costs are worth modeling honestly. If your current vehicle averages significantly fewer miles per gallon than a replacement would, that gap has a real dollar value over annual mileage. Use your actual driving patterns, not EPA estimates, for any comparison.
Safety is a separate consideration that does not reduce neatly to dollars. Drivers with long highway commutes or who frequently carry passengers may weigh the absence of modern driver-assistance features differently than someone driving short distances in light traffic.
How to make the comparison work for your situation
This is general financial information
The figures and frameworks in this article are for educational purposes only. They are not personalized financial advice. Your situation depends on your specific vehicle, local market conditions, loan terms, and insurance rates. A licensed financial adviser or a trusted mechanic can help you weigh the numbers that apply to you.
Start with your repair record for the past two to three years and project forward based on the vehicle's service schedule. Routine maintenance guidance can help identify what is due. For example, understanding actual oil change intervals for your specific vehicle is one piece of a larger picture that includes timing belts, brake service, and fluid changes.
Then build a comparable number for a replacement vehicle: loan payment, higher insurance on a financed car, and the initial registration costs. If the gap between those two totals is small, the status quo often wins on inertia alone. If repairs are climbing toward what a replacement would cost monthly, the trade-off becomes more even.
Neither path is wrong by default. The decision is a math problem, and it is worth treating it as one.
Author
Automotive Life Editorial Team
Automotive Life Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →