
How to Build a Realistic Monthly Car Budget
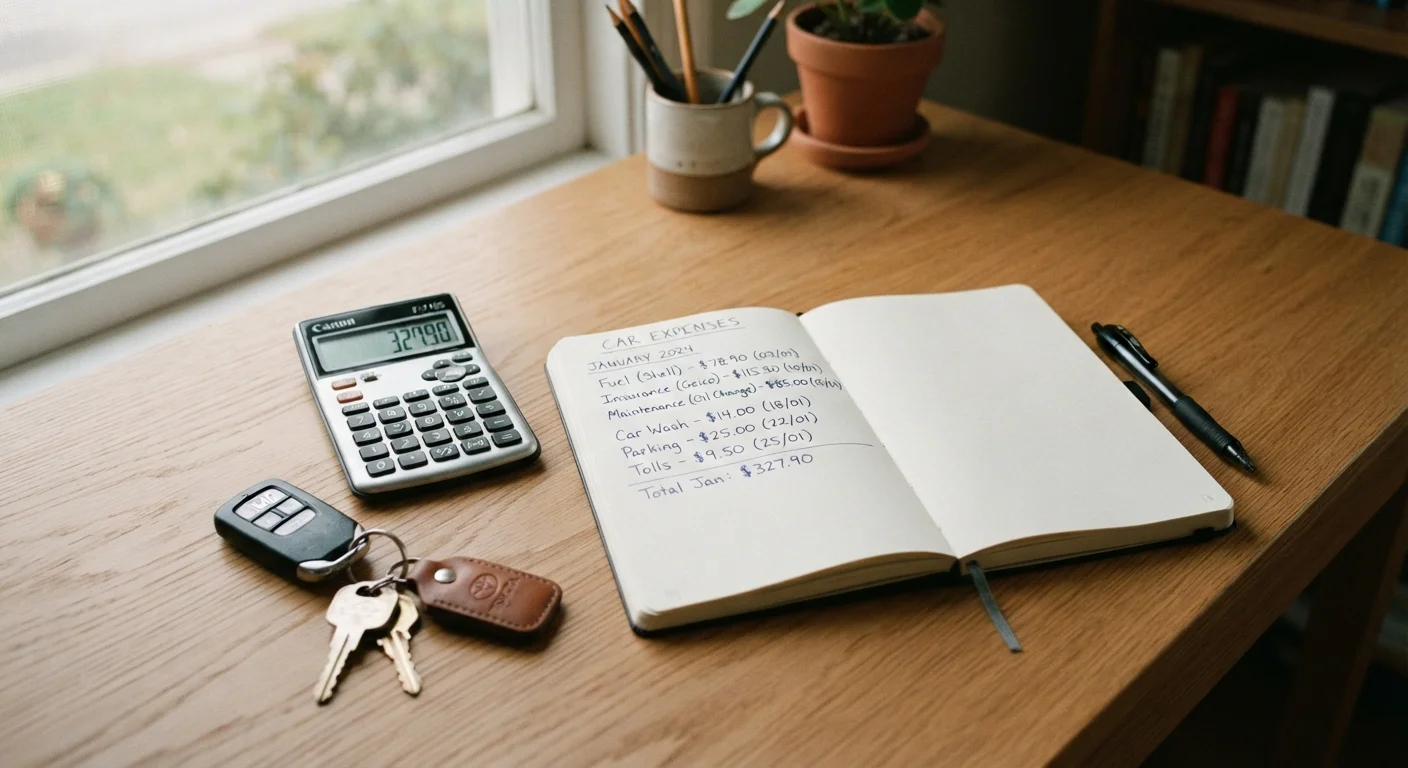
Photo credit: readerspanel.com
In this article
A car payment is just one line item. This step-by-step approach helps you account for insurance, fuel, maintenance, and emergency repairs.
Key Takeaways
- A car payment is typically only 40 to 60 percent of your true monthly vehicle cost.
- Fuel, insurance, maintenance, registration, and repairs all belong in the same budget line.
- Irregular annual costs should be divided by 12 and set aside each month.
- A repair reserve of around $50 to $100 per month can prevent budget-breaking surprises.
- Reviewing your car budget once a year helps you catch costs that have quietly increased.
Why most car budgets fall short
The average American driver thinks of their car payment as their car cost. That single number might cover the loan or lease, but it leaves out the expenses that fill the rest of the month: gasoline, insurance premiums, an oil change here, a new set of wiper blades there, and the registration renewal that arrives every year without warning.
The result is a budget that looks balanced on paper but breaks every time a tire goes flat. Most drivers underestimate what they spend on their vehicle each year, and the gap between perception and reality can run into hundreds of dollars annually.
Building a realistic monthly car budget means accounting for every expense category before money leaves your account, not after. The steps below walk through exactly that process.
What you will need
Step-by-step: building your car budget
Work through these steps in order. You will need about 20 to 45 minutes, a few recent bills, and somewhere to record the numbers. A spreadsheet or even a notepad works fine.
Write down your fixed monthly payment
If you are financing or leasing the vehicle, record the exact monthly payment. If you own the car outright, enter zero. This is the only figure most people start with, and it is the floor, not the ceiling, of your actual cost.
Add your monthly insurance premium
Find your current premium on your declarations page. If you pay semi-annually or annually, divide the total by 6 or 12 to get a monthly figure. Record it alongside your payment.
Estimate your monthly fuel cost
Look at your last two or three months of fuel spending. If you use a debit or credit card at the pump, your statement will show the exact amounts. Average those figures to get a realistic monthly fuel estimate. If your driving varies significantly by season, note that and plan for a higher-mileage month occasionally.
Calculate a monthly maintenance allowance
Add up what you spent on routine maintenance, such as oil changes, filter replacements, tire rotations, and fluid top-offs, over the past 12 months. Divide by 12. That is your baseline monthly maintenance estimate. If you have not tracked this before, a reasonable starting point for a vehicle under five years old is $30 to $60 per month; older vehicles typically run higher.
Build a monthly repair reserve
Repairs are unpredictable in timing, but not in existence. Set a fixed amount each month to transfer to a dedicated savings account. For vehicles under five years old with no known issues, $50 per month is a reasonable starting point. For older or higher-mileage vehicles, consider $75 to $100 or more. You draw from this reserve when a repair bill arrives, then replenish it.
Divide annual fees into monthly contributions
List every vehicle cost that does not appear every month: annual registration, emissions or safety inspection fees, roadside assistance membership, and any annual parking permit. Add these amounts together and divide by 12. Transfer that monthly figure to a savings account so it is ready when the bills arrive. This approach, described in detail for predictable but easy-to-miss annual costs, prevents the scramble that comes with unexpected lump-sum bills.
Add every line and compare to your income
Sum your monthly payment, insurance, fuel, maintenance allowance, repair reserve, and monthly share of annual fees. That total is your realistic monthly car cost. Compare it to your take-home income to see what percentage of your budget the vehicle consumes. Many personal finance frameworks suggest keeping total vehicle costs below 15 to 20 percent of monthly take-home pay, though individual circumstances vary. This is general information, not a prescription tailored to your situation.
Handling irregular and unexpected costs
Two categories resist easy monthly tracking: irregular predictable costs and genuinely unpredictable repairs.
Irregular predictable costs include annual registration, emissions testing, inspection fees, and any roadside assistance membership. These are not surprises, but they rarely show up in a monthly budget. The fix is simple: add them up for the year and divide by 12. Set that amount aside each month in a dedicated savings account. Annual fees and seasonal costs derail budgets regularly, and that monthly savings habit prevents it.
Unpredictable repairs are harder to estimate precisely. A general guideline used in personal finance is to budget at least 1 percent of the vehicle's current market value per year for repairs and maintenance, split into monthly contributions. On a vehicle valued at $15,000, that is roughly $150 per year, or $12.50 per month at minimum. Most mechanics and automotive planning resources suggest a repair reserve closer to $50 to $100 per month for a vehicle older than five years, given that wear items such as brakes, tires, and belts become more frequent.
Use a separate account for irregular costs
Opening a dedicated savings account for vehicle-related irregular expenses, separate from your emergency fund, makes it easier to track the balance and resist spending it elsewhere. Even a basic savings account at the same bank works. Label it clearly so its purpose stays obvious.
For a complete picture of every vehicle cost, the car ownership cost audit checklist covers items that even careful planners tend to miss.
Reviewing and adjusting the budget over time
A car budget built today will drift out of alignment within a year. Insurance premiums change at renewal. Fuel prices shift seasonally. A vehicle that needed one oil change also needs a transmission service at 60,000 miles. Plan a brief annual review to compare what you budgeted against what you actually spent, then adjust each line item accordingly.
If the total monthly cost is higher than you expected, the budgeting basics hub has practical strategies for reworking your overall spending plan without cutting necessary categories. Vehicle expenses also fit within the broader household picture, and an annual household expense checklist can help you see how car costs sit alongside other predictable line items.
This article is for general informational and educational purposes only and does not constitute personalized financial advice. For guidance specific to your financial situation, consult a qualified financial professional.
Author
Automotive Life Editorial Team
Automotive Life Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →