
Financing a Car: Key Terms and What They Mean for Your Wallet
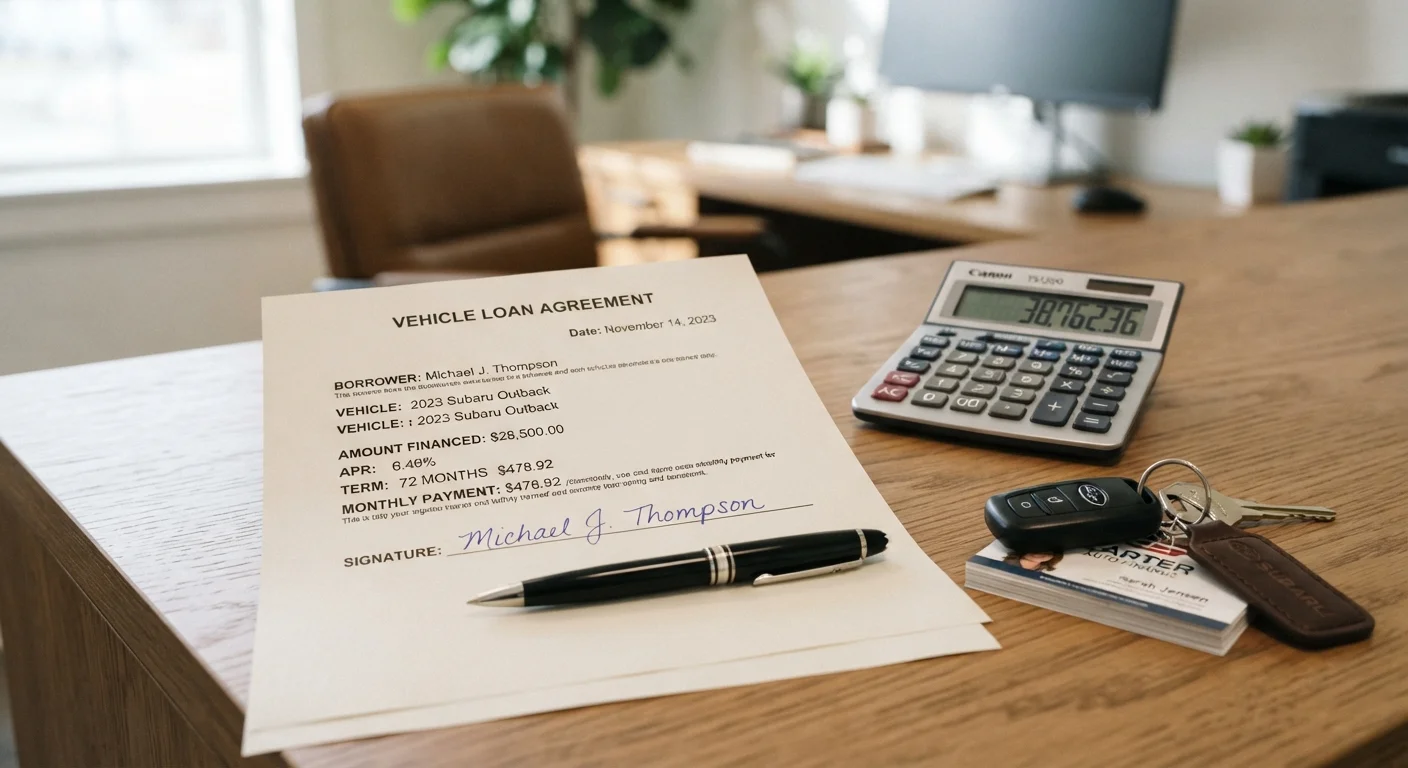
Photo credit: readerspanel.com
In this article
APR, loan term, down payment, principal: understand the core vocabulary of auto financing so you can read any loan offer clearly.
Why loan vocabulary matters before you sign
A car loan offer is a page of numbers and terms. Each term shifts how much you pay, how long you pay it, and what happens if your situation changes. Readers who scan past the monthly payment figure and skip straight to signing often discover the real cost of the loan only after several years of payments.
This reference explains the core vocabulary used in auto loan offers, so you can compare two deals on equal footing. For a closer look at how the numbers compound over time, see how auto loan interest adds up over the life of a loan. For context on the full monthly cost of ownership, building a realistic monthly car budget covers insurance, fuel, and maintenance alongside the loan payment.
Principal
The amount of money borrowed, not counting interest or fees. Your monthly payments reduce this balance over time.
APR (annual percentage rate)
The annualized cost of the loan, combining the interest rate with most mandatory fees. It is more complete than the interest rate alone for comparing loan offers.
Loan term
The number of months over which you repay the loan. Longer terms reduce monthly payments but increase total interest paid.
Amortization
The schedule by which each payment is divided between interest and principal reduction. Interest takes a larger share of early payments.
LTV (loan-to-value ratio)
The loan amount divided by the vehicle's market value, expressed as a percentage. Lenders use it to assess risk.
Underwater (upside-down)
A condition where the outstanding loan balance exceeds the current market value of the vehicle.
Residual value
The projected market value of a vehicle at the end of a lease term, used to calculate lease payments and buyout price.
Down payment
Cash paid upfront at the time of purchase. It reduces the principal and can affect the interest rate a lender offers.
This article is general financial information and education, not personalized financial or legal advice. Consult a licensed financial professional for guidance specific to your situation.
Terms that control the size of your debt
| Typical auto loan terms | 36 to 72 months (Common range offered by banks and credit unions) |
| What APR includes | Interest rate plus most mandatory loan fees |
| LTV threshold often used by lenders | 80% to 100% LTV (General industry practice; varies by lender) |
| When being underwater is most common | Early months of a long-term loan (Result of rapid early depreciation vs. slow principal paydown) |
Principal is the amount you borrow. It is not the same as the vehicle's sticker price. The principal equals the purchase price, minus your down payment, plus any fees or add-ons you roll into the loan. A larger principal means more interest accrues over time, even if the rate stays the same.
Down payment is the cash you pay upfront. A higher down payment reduces the principal directly, which lowers both your monthly payment and the total interest you pay. Lenders may also use a larger down payment as a signal of lower risk, which can affect the rate offered.
Loan term is how many months you have to repay the loan. Common terms run from 36 to 72 months, though some lenders offer longer options. A shorter term means higher monthly payments but less total interest. A longer term reduces the monthly payment but increases the total amount paid. The budgeting basics hub has practical guidance on weighing monthly affordability against long-run cost.
Terms that control the cost of borrowing
Interest rate is the annual percentage charged on the outstanding principal balance. Lenders set it based on factors including your credit score, the loan term, and vehicle age. The interest rate alone does not tell you the full cost of borrowing.
APR (annual percentage rate) combines the interest rate with most mandatory fees into a single annualized figure. Because APR captures more of the loan's true cost than the interest rate alone, it is the more useful number when comparing two loan offers. Note that APR on a loan works differently from APY on a savings account. The APY explainer breaks down that distinction if you want to compare borrowing costs against savings returns.
Amortization describes how each payment is split between interest and principal. Early in a loan, a larger share of each payment goes toward interest. As the principal falls, more of each payment reduces what you owe. This structure means paying off a loan early can reduce total interest significantly, though some loans carry prepayment penalties worth checking for in the contract.
Terms tied to the vehicle's value
LTV (loan-to-value ratio) compares the loan amount to the vehicle's market value, expressed as a percentage. A loan of $18,000 on a car worth $20,000 gives an LTV of 90%. Lenders use LTV to measure risk. A high LTV can result in a higher rate or require additional coverage.
Being underwater (or upside-down) means you owe more on the loan than the vehicle is currently worth. This happens most often in the early months of a long-term loan, when depreciation outpaces principal paydown. If the car is totaled or stolen while you are underwater, a standard insurance payout may not cover the remaining loan balance. Gap coverage, explained in the commonly misunderstood car insurance terms guide, is designed for this situation.
Residual value appears mainly in lease agreements rather than traditional loans. It is the estimated market value of the vehicle at the end of the lease term and affects both your monthly payment and your purchase option price if you decide to buy the car at lease end.
Auto financing touches insurance decisions at several points. The Car Insurance 101 guide covers how lenders typically require comprehensive and collision coverage for the life of the loan.
Author
Automotive Life Editorial Team
Automotive Life Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →