
How Auto Loan Interest Adds Up Over the Life of a Loan
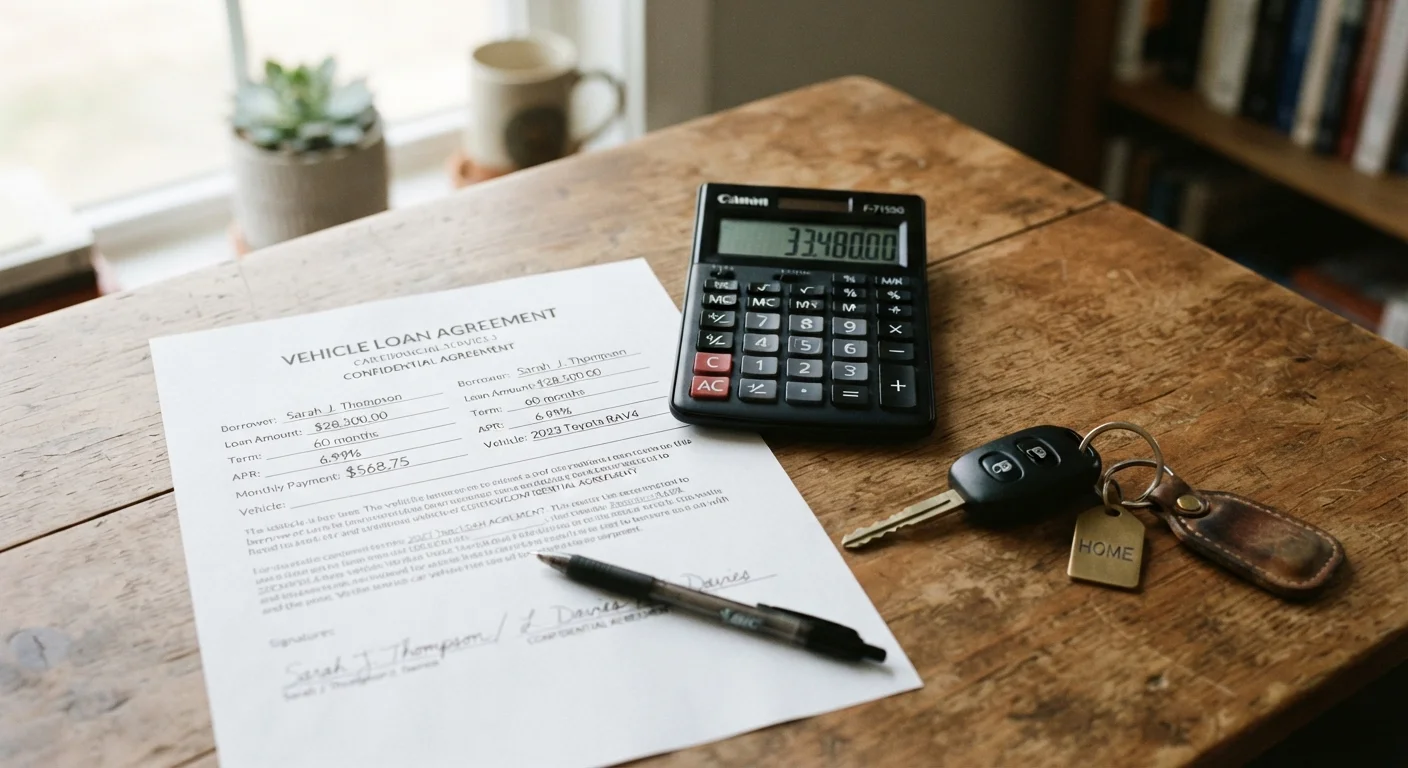
Photo credit: readerspanel.com
In this article
The interest on a multi-year auto loan can add thousands to your total cost. This explainer shows exactly how loan terms affect what you pay.
Key Takeaways
- A longer loan term lowers your monthly payment but increases the total interest you pay.
- Even a small difference in interest rate can add hundreds or thousands of dollars to your total cost.
- Simple interest auto loans accrue interest daily on the remaining balance, so early payments reduce what you owe faster.
- Your credit score is one of the strongest factors affecting the rate a lender offers you.
- Running the full-term total cost, not just the monthly payment, gives a clearer picture of what a loan actually costs.
Why the sticker price is not the full cost
When you finance a vehicle, you agree to repay the amount borrowed plus interest over a set number of months. The purchase price gets the attention, but the interest paid over the loan term is what quietly inflates the real cost of ownership. On a $30,000 loan at a 7% annual rate spread across 60 months, total interest comes to roughly $5,600. Stretch that same loan to 72 months and total interest rises closer to $6,800, even though the rate never changed.
This is one of the most consistent patterns in auto financing: time costs money. The longer the principal sits unpaid, the more interest accrues. Monthly payments drop when you extend the term, which feels like savings, but the lender collects more in the long run. For a full picture of how financing fits into car ownership costs, see the car ownership cost audit that walks through every annual expense category.
Calculate total cost, not just the payment
Before signing a loan agreement, multiply the monthly payment by the number of payments to get the total amount you will pay. Subtract the loan amount to see exactly how much interest you are committing to. Many auto loan calculators available from financial institutions and consumer finance agencies can run this comparison across multiple term lengths in seconds.
How simple interest actually works
The majority of auto loans in the United States use simple interest, not compound interest. That distinction matters. With simple interest, the lender calculates daily interest by dividing the annual rate by 365 and multiplying it by your current principal balance. Pay on time and the math works as the lender projects. Pay late and more interest has accrued between payments, meaning a smaller slice of your next payment goes toward principal.
This mechanism also works in your favor when you pay early or pay extra. Any payment above the scheduled amount reduces principal the day it posts. That lower balance produces less daily interest the next day, and the benefit carries forward. Borrowers who make one extra payment per year can cut several months off a 60-month loan, depending on rate and balance. This is general information; a licensed financial adviser can help you assess whether an accelerated payoff fits your situation.
$5,600+
Estimated interest on a typical 60-month auto loan
Based on a $30,000 loan at 7% annual interest calculated over 60 months using standard simple interest amortization.
84 months
Longest common auto loan term now offered
Seven-year auto loans have become widely available from many lenders as vehicle prices have risen over the past decade.
~2x
Approximate interest cost difference: 84-month vs. 48-month loan
On the same principal and rate, extending the term from 48 to 84 months can nearly double total interest paid over the life of the loan.
How your rate determines the damage
Interest rate has a direct, linear effect on total cost. On a $25,000 loan over 60 months, moving from a 5% rate to a 9% rate increases total interest paid from roughly $3,300 to about $6,000. That $2,700 difference is real money spent on financing, not on the vehicle itself.
Lenders set rates based on several factors. Credit score carries the most weight for most borrowers. A strong credit profile can qualify for rates several percentage points below what a fair-credit borrower receives. Loan term, the age of the vehicle, and the lender type, such as a bank, credit union, or dealership finance arm, also affect the rate offered. Lenders who specialize in auto loans may structure rates differently from general consumer banks. The factors that determine your car insurance premium article covers how credit history shapes another major ownership cost, which shows how the same underlying financial profile affects multiple expense categories simultaneously.
Term length and the true cost trade-off
The 72-month and 84-month loans that became common in recent years make expensive vehicles fit into tight monthly budgets. The monthly payment on an 84-month loan can be $150 to $200 lower than on a 48-month loan for the same vehicle at the same rate. However, the total interest paid over 84 months can be nearly double the interest paid over 48 months.
A second consequence of long terms is negative equity, sometimes called being underwater. Vehicles depreciate rapidly in the first two years. A loan amortized over seven years pays down principal slowly enough that the outstanding balance can exceed the vehicle's market value for several years. If the vehicle is totaled or sold during that window, the owner may owe more than the settlement or sale proceeds cover.
For anyone building a monthly car budget, running the numbers on total interest paid across different term options is a concrete starting point. The monthly car budget guide covers how financing fits alongside insurance, fuel, and maintenance. Fuel is another variable cost worth modeling over time, as the fuel costs over time article explains.
This article is for general informational purposes only and does not constitute financial or legal advice. Consult a licensed financial professional before making borrowing decisions.
Frequently Asked Questions
Author
Automotive Life Editorial Team
Automotive Life Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →