
The Relationship Between Mileage and What Your Car Costs You
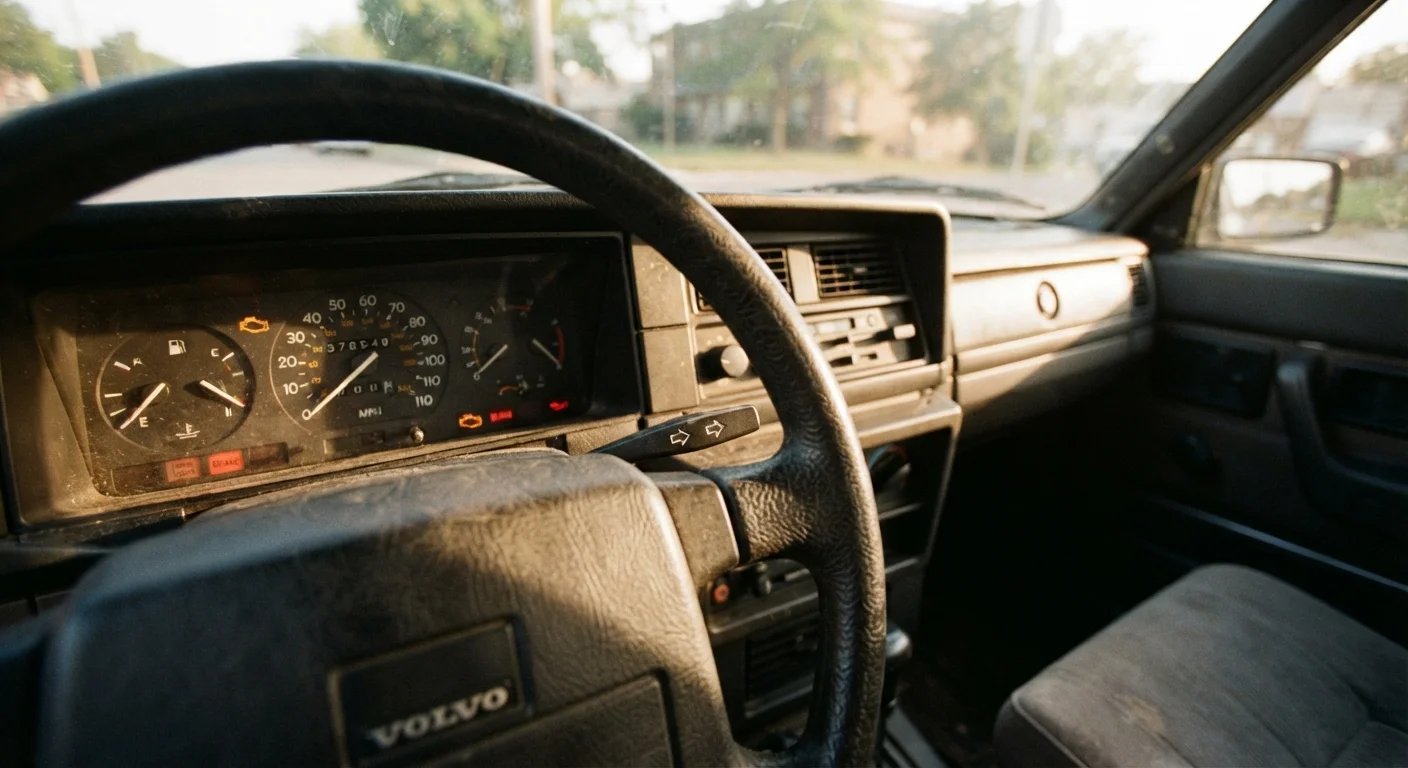
Photo credit: readerspanel.com
In this article
Every mile driven affects depreciation, maintenance intervals, and insurance rates. Learn how annual mileage shapes your total ownership cost.
Key Takeaways
- Annual mileage affects depreciation, insurance premiums, and maintenance intervals all at once.
- Depreciation is the single largest cost for most car owners, and high mileage accelerates it.
- Low-mileage drivers may qualify for reduced insurance rates by reporting accurate annual mileage.
- Manufacturer maintenance schedules are tied to mileage, so driving more means servicing more often.
- Tracking your annual mileage gives you a clearer picture of what your car actually costs you each year.
Why mileage is a cost multiplier
Most car ownership expenses do not sit still. They scale with use. Every mile driven advances your odometer, triggers maintenance thresholds, reduces resale value, and factors into the rate your insurer charges you. Understanding this relationship helps you see your vehicle not just as a transportation tool but as an asset with a predictable cost trajectory.
The full cost of owning a vehicle is rarely obvious at the point of purchase. A $30,000 car does not cost $30,000 to own over five years. It costs that amount plus depreciation, fuel, insurance, maintenance, and repairs. Mileage connects all of these because it is the common variable running through each category.
Mileage vs. age: both matter
Age and mileage work together to determine a vehicle's condition and value. A 10-year-old car with 50,000 miles may have rubber seals and hoses that have deteriorated from age, even though its mechanical wear from use is relatively low. Neither figure alone tells the full story of a vehicle's remaining cost exposure.
Depreciation: the biggest hit
Depreciation is the portion of your car's value that disappears over time, and it is the largest single ownership cost for most drivers. Mileage accelerates it. A vehicle with 80,000 miles on it will be worth less than an otherwise identical vehicle with 40,000 miles, regardless of age, because buyers factor in the remaining usable life of mechanical components.
The first few years of ownership see the steepest depreciation curve. High annual mileage during those early years pushes the vehicle down that curve faster, compressing the window in which you could sell or trade in at a relatively strong value. If your driving needs are consistently above average, you will likely trade in or sell at a lower point on that curve than a low-mileage driver of the same vehicle.
For a practical comparison of how these numbers play out differently depending on whether you bought new or used, see how the total ownership math compares between new and used vehicles.
Maintenance intervals and repair frequency
Vehicle manufacturers publish maintenance schedules based on mileage, not calendar time alone. Oil changes, filter replacements, brake inspections, and fluid flushes all have mileage triggers. Driving 20,000 miles per year means hitting those service points twice as often as someone driving 10,000 miles annually.
The cost difference compounds over time. A driver covering 20,000 miles per year will reach the 60,000-mile major service interval in three years. A driver covering 10,000 miles per year reaches it in six. Both pay the same cost at that interval, but the high-mileage driver pays it years earlier and then continues accumulating service costs at the same accelerated rate.
Beyond scheduled maintenance, higher cumulative mileage correlates with more frequent unplanned repairs. Wear items like brake pads, tires, belts, and suspension components have finite lifespans measured largely in miles. The right maintenance habits can slow that wear, but they cannot stop the underlying math.
How mileage shapes your insurance premium
Insurers use annual mileage as one input when calculating your premium, because a car on the road more hours accumulates more exposure to potential accidents. Drivers who commute long distances or use their vehicles for work purposes typically pay more than those who drive infrequently.
Accurate reporting matters here. When you apply for or renew a policy, you are generally asked for your estimated annual mileage. Underreporting it may reduce your premium in the short term, but it can create complications if you file a claim and the insurer finds a discrepancy. Some insurers now offer usage-based programs that track actual mileage via a device or app, which can benefit genuinely low-mileage drivers with documented proof.
For a broader look at how insurers set rates, see what other factors determine your car insurance premium beyond mileage alone.
~14,500
Average annual miles driven per U.S. driver
The Federal Highway Administration has reported average annual vehicle miles traveled per licensed driver in this range, though figures vary by state and demographic group.
50%+
Value lost in first 3 years of ownership
Industry data from vehicle valuation sources indicates many new vehicles lose more than half their original value within the first three years, with mileage as a primary factor.
2x
Fuel cost difference between 10K and 20K annual miles
At a fixed fuel price and constant fuel economy, doubling annual mileage doubles annual fuel expenditure, with no other variables required.
Fuel costs and the mileage connection
Fuel is the most visible mileage-linked expense because drivers pay it repeatedly and immediately. A vehicle averaging 25 miles per gallon costs significantly less annually at 10,000 miles per year than at 20,000 miles, even if gas prices stay constant. The math is straightforward: twice the miles, twice the fuel spend.
What makes fuel costs harder to predict is that driving behavior affects efficiency as much as distance does. Short trips, stop-and-go traffic, and highway cruising all produce different fuel economy results from the same vehicle. How driving habits shape your fuel bill over time is worth understanding separately, because mileage volume and mileage quality are two different cost levers.
A yearly cost audit that accounts for actual miles driven, average fuel efficiency, and local gas prices will give you a more accurate picture of what you are spending than any estimate based on purchase price alone.
Frequently Asked Questions
Author
Automotive Life Editorial Team
Automotive Life Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →