
New Car vs. Used Car: What the Total Ownership Math Looks Like
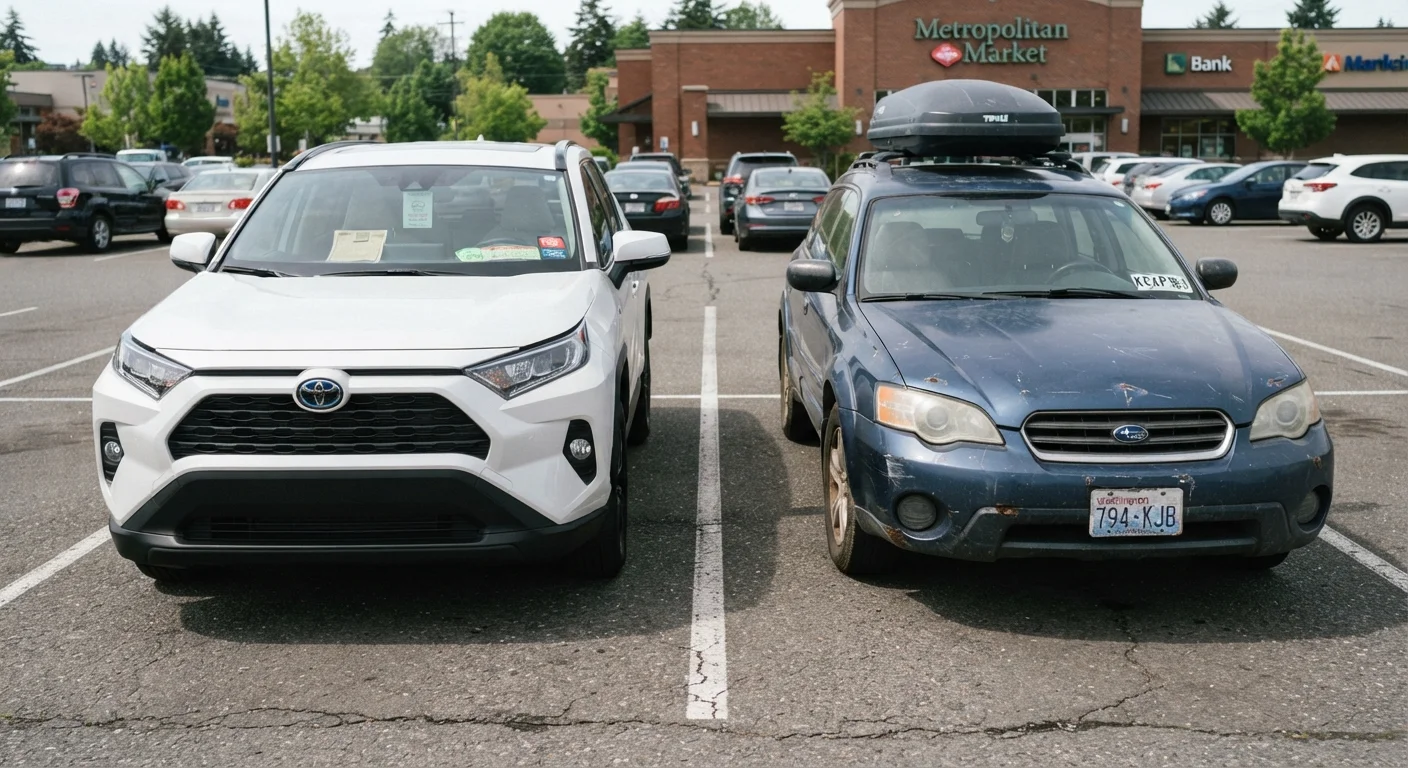
Photo credit: readerspanel.com
In this article
A new car costs more upfront; a used one may cost more to maintain. See how the full financial picture compares over several years of ownership.
Key Takeaways
- A new car depreciates fastest in its first three years, often losing 40 to 50 percent of its value.
- Used cars typically carry higher interest rates on auto loans, which can offset the lower purchase price.
- Insurance premiums are generally lower on older vehicles, though this varies by coverage level and driver profile.
- Maintenance costs tend to rise with mileage and age, especially past 60,000 miles.
- Neither option is universally cheaper; the better choice depends on how long you plan to own the vehicle.
Where the money goes on a new car
The sticker price is only the start. A new car begins depreciating the moment it leaves the lot, and that loss accelerates sharply in years one through three. Industry data from sources including Edmunds has consistently shown that a new vehicle can shed roughly 20 percent of its value in the first year alone, with cumulative depreciation reaching 40 to 50 percent by year three. For a $35,000 vehicle, that is $14,000 to $17,500 in lost equity before a single major repair bill arrives.
Financing a new vehicle typically comes with a lower annual percentage rate (APR) than a used-car loan. Lenders price new-car loans as lower risk because the collateral is easier to value. That rate advantage can meaningfully reduce total interest paid, especially on five- or six-year terms. See how loan terms affect total interest paid for a closer look at how this compounds.
On the maintenance side, a new car under a factory warranty shifts most repair costs to the manufacturer for at least the first three years or 36,000 miles, depending on the powertrain coverage. That predictability has real value, though it does not cover tires, brakes, or consumables.
The actual cost picture on a used car
| Cost factor | New car | Used car (2-4 years old) | |
|---|---|---|---|
| Purchase price | Higher | Lower | |
| Depreciation in year 1 | Steepest (up to 20%) | Already absorbed | |
| Loan interest rate | Generally lower | Generally higher | |
| Insurance (full coverage) | Higher premium | Lower premium | |
| Factory warranty coverage | Full coverage at purchase | Partial or expired | |
| Near-term repair risk | Low | Moderate to higher | |
| Registration fees | Higher (value-based) | Lower | |
| Long-term hold value | Better if held 7+ years | Depends on mileage | |
| Total 5-year cost | Higher upfront, stable costs | Lower upfront, rising costs |
A used vehicle bought in the two-to-four-year-old range lets someone else absorb the steepest depreciation. The purchase price is lower, monthly payments are smaller, and the car may still carry some remaining factory coverage or a certified pre-owned warranty.
However, used-car loan rates run higher. According to Federal Reserve consumer credit data, the spread between new and used auto loan rates has historically been two to four percentage points. On a $20,000 used-car loan at a rate two points above a comparable new-car loan, a buyer can pay several hundred dollars more in interest over a four-year term, which narrows the purchase-price advantage.
Older vehicles also accumulate major scheduled expenses like timing belt replacements, transmission service, and brake overhauls that new-car buyers typically face further down the road. Annual mileage shapes these intervals directly: a used car already at 60,000 miles may be close to several of them.
Insurance and registration: the gap is real but often misread
Comprehensive and collision coverage on a new car costs more because the insurer is covering a higher-value asset. On an older vehicle, many owners drop comprehensive or raise deductibles once the car is paid off, which lowers premiums. That said, a financed used car typically still requires full coverage per lender requirements, so the savings are not automatic.
Registration fees in most states are tied to vehicle value or model year, which means a newer car generally carries higher annual fees. The difference is modest on its own, but it adds to the total over a five-year hold.
For a full accounting of every line item, the car ownership cost audit is a practical starting point.
How the math shifts with ownership length
Run a five-year total cost estimate before deciding
Add up estimated loan payments (including interest), insurance premiums, registration fees, and a realistic maintenance budget for each option you are considering. A used car with a higher loan rate and a known upcoming service interval may cost more over five years than the purchase price difference suggests. Free cost-of-ownership calculators from sources like Consumer Reports or Edmunds can help structure this math before you commit.
A driver who trades in every three years is almost always better served by a used car: they absorb less depreciation and keep repair risk low by staying in the lower-mileage range. The new-car loan rate advantage does not fully compensate for the value lost in those first three years.
A driver who holds a vehicle for eight to ten years changes the equation. By year five or six, a new car bought at loan origination is paid off and retains enough mechanical reliability that the owner is essentially driving on equity. A used car at the same age and higher mileage may generate repair costs that approach or exceed what the owner saved at purchase.
This is why the decision to keep a car longer or trade it in deserves its own analysis rather than a default answer. The total cost of ownership across fuel, insurance, financing, and maintenance is the number that matters, not the purchase price alone.
Author
Automotive Life Editorial Team
Automotive Life Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →