
The 50/30/20 Rule vs. the Envelope Method: Which Budgeting Framework Fits Your Life
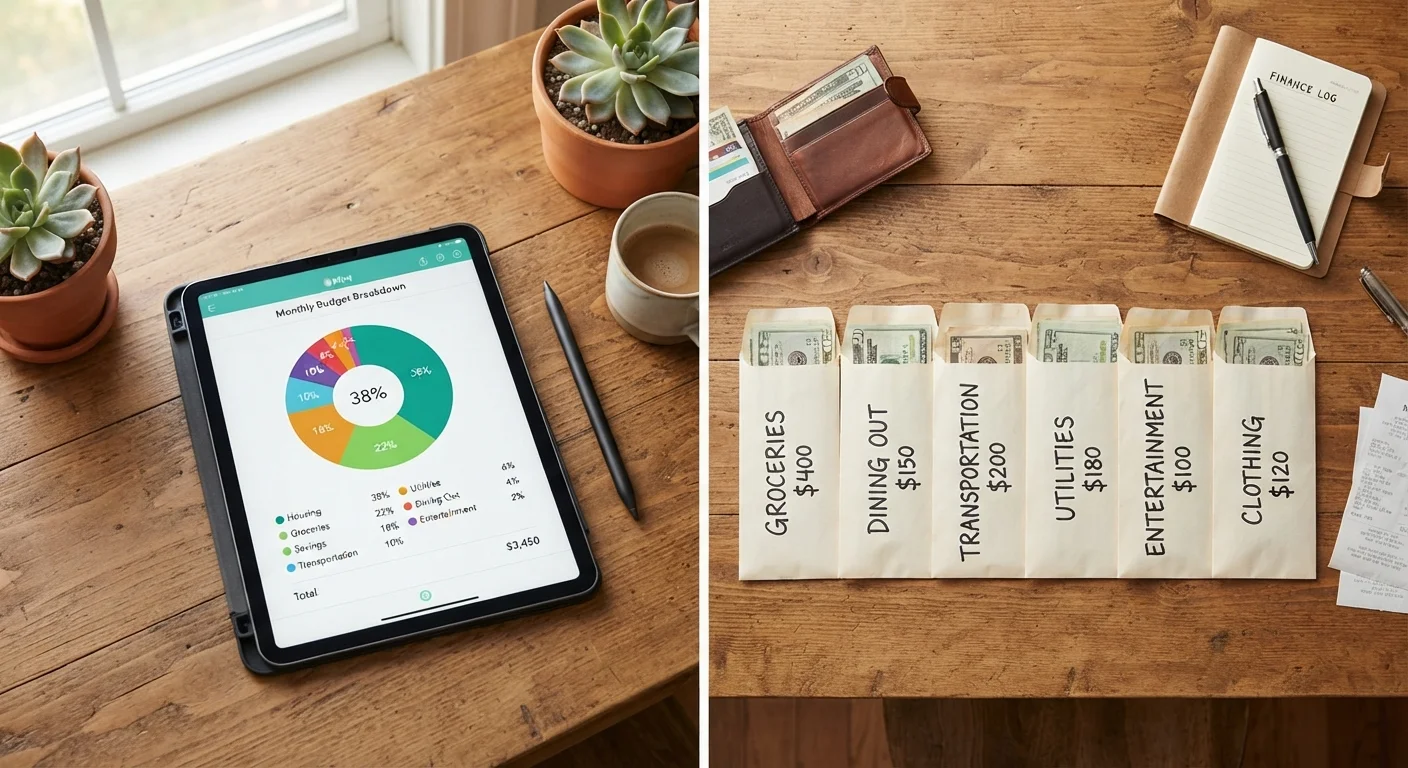
Photo credit: readerspanel.com
In this article
Two popular budgeting frameworks, one key question: which structure actually helps you save? A clear side-by-side look at how each approach works.
Key Takeaways
- The 50/30/20 rule divides after-tax income into needs (50%), wants (30%), and savings or debt repayment (20%).
- The envelope method uses physical or virtual cash envelopes to cap spending in discrete categories.
- The 50/30/20 rule works best as a high-level guide; the envelope method provides category-level friction.
- Neither framework suits every income level or spending pattern without some adjustment.
- You can combine elements of both approaches to fit your actual financial situation.
How each framework is structured
The 50/30/20 rule, popularized in personal finance writing, divides your after-tax income into three categories: 50% toward needs (housing, groceries, utilities, insurance), 30% toward wants (dining out, subscriptions, entertainment), and 20% toward savings and debt repayment beyond minimums. The appeal is speed. You do not need a line item for every purchase. You just check whether your broad spending is landing in the right proportions.
The envelope method works differently. You divide your income into specific spending categories and allocate a fixed cash amount to each. Historically, that meant physical envelopes stuffed with bills. When the grocery envelope is empty, grocery spending stops until next pay period. Digital versions replicate this logic using budgeting apps or separate sub-accounts, but the core mechanic is the same: each category has a hard ceiling.
| Criterion | 50/30/20 rule | Envelope method |
|---|---|---|
| Setup time | Low, three categories only | Moderate, requires category list |
| Category granularity | Broad buckets | Specific per-category limits |
| Spending friction | Low, mental check only | High, hard cap per envelope |
| Works with irregular income | Less predictable | Fund from what you have |
| Best visibility into overspending | Category-level blind spots | Immediate, per-category |
| Ease of ongoing maintenance | Monthly review sufficient | Requires each-period allocation |
Both frameworks are described in detail across budgeting basics resources, though the mechanics above cover what you need to compare them directly.
Where each approach tends to succeed
The 50/30/20 rule handles the cognitive overhead well. If you earn a steady salary and your fixed costs are stable, confirming that your spending is roughly within the three buckets takes minutes per month. It also adapts across income levels without requiring you to rebuild a category list every time your life changes.
The envelope method succeeds where willpower has already failed. The physical or virtual constraint removes the decision entirely. There is no mental negotiation about whether the concert ticket counts as a want or whether it comes from savings. The envelope either has money in it or it does not. For people who consistently overspend on dining, clothing, or discretionary categories, that friction is the point.
For households managing tight margins, stability-focused budgeting strategies may be worth reading alongside either framework, since both the 50/30/20 rule and the envelope method assume there is some slack to allocate.
Where each approach runs into problems
The 50% needs threshold may not fit your situation
In many U.S. metro areas, housing alone can consume 35% to 45% of take-home pay for median earners. If your fixed costs genuinely exceed 50% of income, the 50/30/20 rule still provides a directional target, but hitting it may require income changes rather than spending adjustments. Adjust the percentages to reflect your actual constraints rather than abandoning the framework entirely.
The 50/30/20 rule's broad categories can mask real problems. A household spending 49% on needs and 31% on wants is technically within the guidelines on the needs side, but the wants number tells a different story. Without category-level visibility, small overages compound invisibly. The framework also struggles when needs genuinely exceed 50% of income, which is common in high-cost-of-living areas. Forcing real spending into an aspirational percentage does not make it fit.
The envelope method has a different failure mode: it requires consistent setup and discipline to refill accurately each period. Miss a few months of envelope allocation and the system collapses. It can also get complicated fast if you have many spending categories. Deciding whether a veterinary visit comes from the pets envelope or an emergency envelope is a real question the system requires you to answer in advance.
For a broader look at how format affects budgeting behavior, paper versus digital budget tools covers how the medium you use changes what you actually track.
Mixing the two frameworks
Some people use the 50/30/20 rule to set overall allocation targets and the envelope method to enforce limits within the wants category only. This keeps the system light at the top while adding friction exactly where overspending typically occurs. If your needs and savings are on autopilot through direct deposit and automatic transfers, the envelope approach can cover just the discretionary slice.
If you prefer working with percentages rather than fixed dollar amounts, percentage-based versus dollar-amount budgeting walks through the trade-offs in more detail. Planning annual household expenses in advance also helps both frameworks work more reliably. A home expense checklist can surface predictable costs that otherwise land as surprises.
This article is for general informational purposes only and does not constitute personalized financial advice. For decisions specific to your financial situation, consult a qualified financial professional.
Author
Smart Shopping Editorial Team
Smart Shopping Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →