
What Travel Insurance Actually Covers (And the Gaps People Overlook)
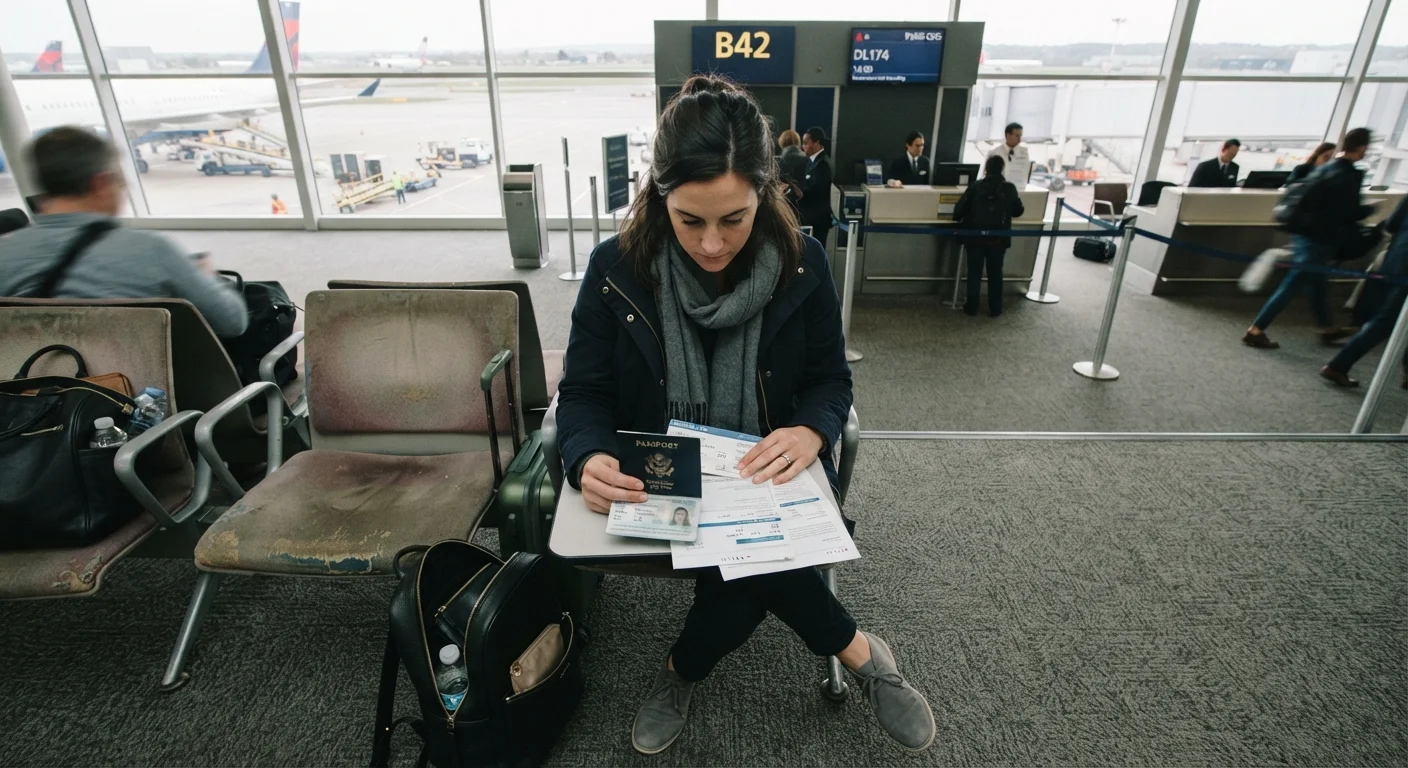
Photo credit: readerspanel.com
In this article
Travel insurance isn't one-size-fits-all. This explainer breaks down common coverage types, exclusions, and what to verify before your trip.
Key Takeaways
- Trip cancellation and trip interruption are different benefits with different reimbursement rules.
- Emergency medical coverage abroad is one of the most financially significant benefits, since many domestic health plans have limited or no international coverage.
- Pre-existing medical conditions are frequently excluded unless a waiver is purchased within a set window after booking.
- Cancel-for-any-reason coverage costs more and typically reimburses only a portion of prepaid, non-refundable costs.
- Adventure sports, pandemics, and government travel advisories each have unique exclusion patterns across different policies.
- Always verify current entry requirements and travel advisories through official government sources before departure.
The core coverage types in most travel policies
Travel insurance is not a single product. Most packages bundle several distinct benefits, and each one has its own conditions and limits.
Trip cancellation reimburses prepaid, non-refundable costs if you cancel before departure for a covered reason. Common covered reasons include your own serious illness or injury, a death in your immediate family, severe weather that makes the destination inaccessible, or jury duty. The list of covered reasons is finite and spelled out in the policy; anything outside it is not eligible.
Trip interruption applies after you have already departed. If you must cut the trip short for a covered reason, this benefit can reimburse unused prepaid costs and the cost of an unexpected return flight. Interruption limits are sometimes higher than cancellation limits because last-minute flights are expensive.
Emergency medical and evacuation coverage is frequently the most financially consequential benefit for international travelers. Many US health plans pay little or nothing abroad, and Medicare generally has no international coverage. A serious illness or accident in a foreign country can produce hospital bills in the tens of thousands of dollars before medical evacuation costs are even added. Emergency evacuation alone, particularly from remote areas, can exceed $100,000 according to general industry figures cited by the US Travel Insurance Association.
Baggage loss and delay pays for lost, stolen, or damaged luggage up to a stated limit, and sometimes covers essential purchases if bags are delayed beyond a set number of hours. Per-item limits within the baggage benefit often cap reimbursement for electronics, jewelry, or cameras well below their replacement value.
See our guide to building a complete travel budget for context on how insurance fits into overall trip costs.
The gaps travelers most often overlook
Policies are defined as much by what they exclude as by what they cover. Several exclusions catch travelers off guard.
Pre-existing medical conditions are excluded from most standard policies unless you purchase a waiver. To qualify for that waiver, you typically must buy the policy within 14 to 21 days of your first trip deposit and be medically fit to travel at purchase. Miss that window and a flare-up of a known condition may not be covered.
Adventure and hazardous activities carry their own exclusion in many standard plans. Skiing, scuba diving, rock climbing, and similar activities may require a separate rider. If physical activities are part of your itinerary, the exclusions section of any policy deserves a careful read before you buy.
Travel advisories and political events create another gray area. If the US government issues a travel advisory before you purchase a policy, that destination's risks may already be excluded. Policies bought after an advisory is issued for a specific country often will not cover losses related to that advisory. This also applies to civil unrest and some natural disasters that were foreseeable at purchase time.
Pandemics and epidemics have uneven treatment across policies. Coverage related to illness from a declared pandemic, or trip cancellations tied to one, is offered as an add-on by some insurers and excluded entirely by others. Read the policy language directly rather than relying on a summary page.
Read the exclusions list first
Most policy comparison tools highlight benefits, not exclusions. Go directly to the exclusions section of the policy document before purchasing. If the language is unclear, contact the insurer for written clarification. Verbal assurances are not binding.
For comparison, the way exclusions work in travel policies is structurally similar to exclusions in auto or pet coverage. Our overview of pet insurance tradeoffs and our guide to car insurance terminology both walk through how to read exclusion language in other policy types.
What to check before you buy
Comparing policies by price alone misses most of what matters. A few practical checks before purchase can prevent surprises during a claim.
Read the definitions section. Terms like "immediate family," "pre-existing condition," and "common carrier" have precise meanings within each policy that may differ from everyday usage. A covered cancellation tied to a family member's illness depends entirely on how the policy defines who qualifies as family.
Check the medical coverage limit and whether it includes evacuation. A policy with a $25,000 medical limit may be adequate for a weekend trip to Canada and insufficient for a month in Southeast Asia.
Look at the time-sensitive upgrade windows. Pre-existing condition waivers and cancel-for-any-reason upgrades must typically be added within days of your initial trip deposit. Waiting until just before departure usually means losing access to those options.
Verify what documentation a claim requires. Airline delay certificates, itemized medical bills, police reports for theft: knowing what evidence you will need before an incident means you can gather it in real time rather than scrambling after the fact.
For anything involving entry requirements, vaccination rules, or government travel advisories, always check official government sources such as travel.state.gov before and close to your departure date. Those conditions change, and no insurance policy substitutes for current, authoritative information.
Our travel myth-check article covers other common planning assumptions that can create costly surprises on the road.
This article is for general informational purposes only and is not insurance or financial advice. Policy terms, exclusions, and costs vary by insurer. Consult a licensed insurance professional and read your policy documents carefully before making any coverage decisions.
Frequently Asked Questions
Author
Travel & Adventure Editorial Team
Travel & Adventure Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →